
BUS-110 · Lesson 4 of 12 · 38 min
Sales taxes, invoices and discounts
Every sale between businesses produces an invoice, and nearly every invoice involves three kinds of calculation: discounts off a list price, sales tax on the result, and the terms that say when payment is due and what reward is offered for paying early. Getting these right matters to both sides. A buyer who misses an early-payment discount is paying an expensive hidden interest rate, and a seller who charges the wrong tax can owe the difference out of its own pocket. This lesson covers sales taxes, trade discounts, cash discounts and the anatomy of an invoice.
Sales taxes
The United States has no federal sales tax. Sales taxes are set by states, and in most states counties, cities and special districts add their own local rates, so the combined rate depends on the exact location of the sale. Five states (Alaska, Delaware, Montana, New Hampshire and Oregon) have no statewide sales tax, although Alaska allows local sales taxes. The rates below are state base rates at the time of writing (October 2026); always add the local rate for the delivery address.
| State | State base rate | Local taxes |
|---|---|---|
| California | 7.25 % | Yes; many combined rates are 8 % to 10 %+ |
| Texas | 6.25 % | Yes; local add-ons up to 2 % |
| New York | 4 % | Yes; New York City combined rate is 8.875 % |
| Florida | 6 % | Yes; county surtaxes |
| Illinois | 6.25 % | Yes; Chicago combined rates exceed 10 % |
| Colorado | 2.9 % | Yes; local rates are often larger than the state rate |
| Oregon, Montana, New Hampshire, Delaware | None | No general sales tax |
| Alaska | None | Local sales taxes in some boroughs and cities |
US sales taxes are retail sales taxes: they are charged once, on the sale to the final user. A business buying goods to resell gives the seller a resale certificate and pays no sales tax on that purchase; it collects tax from its own customers instead. When a buyer purchases taxable goods without paying sales tax, for example from an out-of-state seller that did not collect it, the buyer usually owes use tax at the same rate. Since the Supreme Court's 2018 decision in South Dakota v. Wayfair, states can require remote sellers to collect tax once they pass an economic threshold, commonly $100,000 of sales into the state.
Sales tax arithmetic is simple percentage work. Tax = taxable amount × rate, and the total = taxable amount × (1 + rate). The reverse calculation, recovering the pre-tax price from a tax-inclusive total, divides by (1 + rate). A frequent mistake is to take the rate off the total instead, which gives too small a price and too much tax.
Worked problem
Tax in different places
An online retailer sells a $480 office chair. What is the total price delivered to Houston, where the combined rate is 8.25 %, to Portland, Oregon, and to a New York City address at 8.875 %?
Show solution
- Houston (8.25 %): tax = 0.0825 × $480 = $39.60; total $519.60.
- Portland (no sales tax): total $480.00.
- New York City (8.875 %): tax = 0.08875 × $480 = $42.60; total $522.60.
Answer: The same chair costs $480.00 in Portland and $522.60 in New York City, a difference of over $42, purely because of sales tax.
Worked problem
Backing tax out of a total
A receipt from a Texas store shows a total of $541.25 including tax at a combined rate of 8.25 %. How much was the price before tax, and how much tax was charged?
Show solution
- Price before tax = $541.25 ÷ 1.0825 = $500.00.
- Tax = $541.25 − $500.00 = $41.25.
- Check: 8.25 % of $541.25 would be $44.65, which is the wrong answer you get by taking the rate off the total.
Answer: The price was $500.00 and the tax was $41.25.
Trade discounts
Manufacturers and wholesalers often publish a list price (a catalog or suggested retail price) and then give each type of customer a trade discount off that list. Retailers might get 40 %, wholesalers 50 %, and large buyers an extra discount on top. Trade discounts are not a reward for anything; they are simply how the seller sets the price for each class of buyer. Publishing one list and varying the discounts lets the seller change prices without reprinting the catalog.
When several trade discounts are offered in a chain, such as 25 %, 10 % and 5 % (often written 25/10/5), each discount applies to the price left after the previous one. The discounts must not be added. Instead, multiply the complements to get the net cost factor (NCF). The single equivalent discount is one minus the NCF.
Worked problem
A chain discount
A distributor lists a commercial coffee grinder at $1,250 and offers a restaurant supply store a chain discount of 25/10/5. What is the net price, and what single discount is equivalent to the chain?
Show solution
- Net cost factor = 0.75 × 0.90 × 0.95 = 0.64125.
- Net price = $1,250 × 0.64125 = $801.56.
- Single equivalent discount = 1 − 0.64125 = 0.35875, or 35.875 %.
- Adding the discounts would give 40 % and a net price of $750, which is wrong.
Answer: The store pays $801.56, a single equivalent discount of 35.875 %, which is less than the 40 % the three discounts appear to add up to.
The order of the discounts in a chain does not matter, because multiplication is commutative: 25/10/5 gives the same price as 5/10/25. What matters is that each later discount is taken from a smaller base.
Worked problem
Comparing two suppliers
Supplier A offers a product at a list price of $640 less 30/10. Supplier B offers the same product at a list price of $600 less 20/5/5. Which is cheaper, and by how much?
Show solution
- Supplier A: NCF = 0.70 × 0.90 = 0.63; net price = $640 × 0.63 = $403.20.
- Supplier B: NCF = 0.80 × 0.95 × 0.95 = 0.722; net price = $600 × 0.722 = $433.20.
- Difference = $433.20 − $403.20 = $30.00.
Answer: Supplier A is cheaper by $30.00, even though its list price is higher. Compare net prices, not list prices or the number of discounts.
Cash discounts and terms of payment
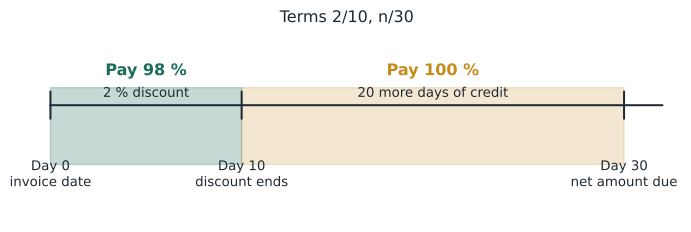
Once goods are sold on credit, the invoice states the terms of payment. A common form is 2/10, n/30, read as 'two ten, net thirty': the buyer may take a 2 % discount if it pays within 10 days of the invoice date; otherwise the full (net) amount is due within 30 days. The 10-day window is the discount period and the 30 days is the credit period. Variations include 1/15, n/45; 2/10 EOM (10 days after the end of the month); and n/60 with no discount at all.
Worked problem
Taking a cash discount
An invoice for $8,400 is dated March 3 with terms 2/10, n/30. (a) What is the last day for the discount, and how much is paid then? (b) When is the net amount due?
Show solution
- (a) The discount period ends 10 days after March 3, on March 13. Payment = $8,400 × 0.98 = $8,232.00.
- (b) The net amount of $8,400 is due 30 days after March 3, on April 2.
Answer: Pay $8,232.00 by March 13, or $8,400.00 by April 2.
A buyer that cannot pay the whole invoice inside the discount period may make a partial payment. The usual rule is that each dollar paid within the discount period settles more than a dollar of the invoice. With a 2 % discount, a payment of $98 settles $100 of the invoice, so the amount credited is the payment divided by (1 − d).
Worked problem
A partial payment
For the same $8,400 invoice, the buyer pays $5,000 on March 12. How much is credited to the account, and what balance is still owed?
Show solution
- Amount credited = $5,000 ÷ 0.98 = $5,102.04.
- Balance owed = $8,400.00 − $5,102.04 = $3,297.96, due by April 2.
Answer: The payment of $5,000 settles $5,102.04 of the invoice, leaving $3,297.96 to pay by April 2.
The real cost of skipping the discount
A 2 % discount sounds small, but it is a large reward for paying 20 days early. If the buyer skips the discount and pays on day 30, it is in effect borrowing $98 from the supplier for 20 days at a cost of $2. Annualizing that cost shows how expensive it is.
Worked problem
The implied interest rate of 2/10, n/30
What annual rate does a buyer effectively pay by skipping the discount on 2/10, n/30 terms? Its bank offers a line of credit at 9 %. Should it borrow to take the discount?
Show solution
- Cost per dollar borrowed = 0.02 ÷ 0.98 = 0.020408.
- Days of extra credit = 30 − 10 = 20.
- Implied annual rate = 0.020408 × 365 ÷ 20 = 0.3724, or about 37.2 % (simple interest).
- Borrowing at 9 % to pay early is far cheaper than paying 37.2 % in lost discount.
Answer: Skipping the discount costs about 37.2 % a year. The buyer should borrow at 9 % and take the discount.
Reading and building an invoice
An invoice lists each item with its quantity and unit price; the product of the two is called the extension. The extensions are added to a subtotal, trade discounts are applied, shipping charges are added, and sales tax is calculated on the taxable amount. The terms of payment and shipping terms appear at the top or bottom. FOB (free on board) shipping point means the buyer owns the goods once they leave the seller and pays the freight; FOB destination means the seller pays the freight and owns the goods until they arrive.
Worked problem
Building an invoice
A Columbus, Ohio, office supplier invoices a customer for 40 desk lamps at $18.75, 12 filing cabinets at $64.50 and 6 office chairs at $129.00, less a 20 % trade discount. Freight of $85.00 is prepaid and added (FOB shipping point) and, in this example, is not taxed. Sales tax at a combined 7.25 % applies to the merchandise. Terms are 2/10, n/30, and the cash discount applies to the merchandise only. What is the invoice total, and what should the customer pay within 10 days?
Show solution
- Extensions: 40 × $18.75 = $750.00; 12 × $64.50 = $774.00; 6 × $129.00 = $774.00. Subtotal = $2,298.00.
- Trade discount = 20 % × $2,298.00 = $459.60; net merchandise = $1,838.40.
- Sales tax = 7.25 % × $1,838.40 = $133.28.
- Invoice total = $1,838.40 + $85.00 + $133.28 = $2,056.68.
- Cash discount = 2 % × $1,838.40 = $36.77. Payment within 10 days = $2,056.68 − $36.77 = $2,019.91.
Answer: The invoice total is $2,056.68, or $2,019.91 if paid within 10 days. If the customer bought the goods for resale and gave a resale certificate, no sales tax would be charged.
# Invoice calculator: extensions, trade discount, freight, tax, cash discount
items = [("Desk lamp", 40, 18.75), ("Filing cabinet", 12, 64.50), ("Office chair", 6, 129.00)]
trade, freight, cash = 0.20, 85.00, 0.02
subtotal = sum(q * p for _, q, p in items)
net = round(subtotal * (1 - trade), 2)
for rate, freight_taxed, label in [(0.13, True, "Ontario HST 13%"), (0.0725, False, "Ohio 7.25%")]:
    base = net + (freight if freight_taxed else 0)
    tax = round(base * rate, 2)
    total = round(net + freight + tax, 2)
    early = round(total - net * cash, 2)
    print(f"{label}: subtotal {subtotal:.2f}, net {net:.2f}, tax {tax:.2f}, total {total:.2f}, pay early {early:.2f}")
print(f"Implied rate of skipping 2/10, n/30: {cash / (1 - cash) * 365 / 20:.1%}")Ontario HST 13%: subtotal 2298.00, net 1838.40, tax 250.04, total 2173.44, pay early 2136.67 Ohio 7.25%: subtotal 2298.00, net 1838.40, tax 133.28, total 2056.68, pay early 2019.91 Implied rate of skipping 2/10, n/30: 37.2%
Common mistakes
MistakeAdding chain discounts, such as treating 25/10/5 as 40 %.
InsteadMultiply the complements: 0.75 × 0.90 × 0.95 = 0.64125.
MistakeTaking the tax rate off a tax-inclusive total.
InsteadDivide the total by (1 + rate) to find the price before tax.
MistakeCrediting only the amount paid when a partial payment is made in the discount period.
InsteadCredit the payment divided by (1 − d).
MistakeTreating a 2 % cash discount as trivial.
InsteadAnnualized, skipping 2/10, n/30 costs about 37 % a year.
MistakeComparing suppliers by list price.
InsteadCompare net prices after all discounts, plus freight terms.
Summary and key terms
- US sales taxes are set by states and localities; five states have no statewide sales tax.
- Price before tax = total ÷ (1 + rate).
- Trade discounts set prices for classes of buyers; chain discounts multiply.
- Terms such as 2/10, n/30 reward early payment.
- Partial payments in the discount period are credited at payment ÷ (1 − d).
- Skipping a cash discount is usually very expensive borrowing.
- An invoice moves from extensions to subtotal, discounts, freight, tax and terms.
- List price
- The published catalog or suggested price before discounts.
- Trade discount
- A reduction from list price given to a class of buyer.
- Net cost factor
- The product of the complements of a chain of discounts.
- Single equivalent discount
- One discount that has the same effect as a chain.
- Cash discount
- A reduction for paying within the discount period.
- Discount period
- The days within which a cash discount may be taken.
- Credit period
- The days within which the full invoice must be paid.
- Extension
- Quantity × unit price on an invoice line.
- FOB shipping point
- Terms under which the buyer owns goods in transit and pays freight.
- Combined rate
- The total of all sales taxes that apply at one location.
Practice problems
Work each problem on paper first, then reveal the answer to check.
What is the total on a $250 purchase at a combined rate of 6.5 %?
Show answer
$266.25.
A receipt totals $646.20 at a combined rate of 7.7 %. What was the pre-tax price?
Show answer
$600.00.
What is the net cost factor of 30/20/10?
Show answer
0.504.
What single discount equals 30/20/10?
Show answer
49.6 %.
A list price of $2,400 less 15/10. What is the net price?
Show answer
$1,836.
An invoice of $3,600 dated June 18 has terms 1/15, n/45. How much is due on July 2?
Show answer
$3,564.
On terms 2/10, n/30, a buyer pays $1,960 within the discount period. How much of the invoice is settled?
Show answer
$2,000.
What is the implied annual rate of skipping the discount on 1/10, n/30?
Show answer
About 18.4 %.
Under FOB destination, who pays the freight?
Show answer
The seller.
Six items at $42.50 less 10 %. What is the net amount?
Show answer
$229.50.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.