
CON-320 · Lesson 9 of 12 · 32 min
Financing: credit lines, loans and leasing
Even a well-run contractor needs outside money at times: to carry receivables during a busy season, to buy equipment, to fund growth or to bridge a slow-paying owner. The choice of financing matters beyond its interest cost, because each form of borrowing affects working capital, equity and the ratios that sureties use to set bonding capacity. This lesson describes the main sources of financing for contractors, how banks size and police an operating line of credit, how term loans and equipment finance work, how leases are accounted for and how they look to a surety, and what owners' money in the form of equity and shareholder loans does for the firm.
Interest rates in this lesson are illustrative. Actual rates depend on the central bank's policy rate, the lender's prime rate and the contractor's risk.
Sources of financing
| Source | Typical use | Effect on working capital and equity |
|---|---|---|
| Retained earnings | Everything; the cheapest and most valued by sureties | Increases equity and working capital |
| New equity from owners | Growth, recovery from losses | Increases equity and working capital |
| Shareholder loans, subordinated to the surety and bank | Bridging, tax-efficient owner funding | Often treated by sureties as equity if formally subordinated and postponed |
| Operating line of credit | Short-term swings in receivables and payroll | Draws are current liabilities; no improvement in working capital |
| Term loan | Equipment, buildings, permanent working capital | Long-term portion improves working capital compared with using the line |
| Equipment financing and leases | Specific machines | Spread cost over the asset's life; lease accounting depends on the framework |
| Receivables financing or factoring | Firms that cannot get a bank line | Expensive; sureties may view it as a sign of weakness |
| Supplier and subcontractor credit | Day-to-day operations | Payables; part of the normal operating cycle |
A recurring theme is the difference between short-term and long-term financing. Money borrowed on the operating line appears as a current liability, so using it to buy equipment or cover a loss reduces working capital just as paying cash would. Financing a long-lived asset with long-term debt keeps the current portion small and protects working capital. Matching the term of the financing to the life of what it pays for is a basic rule that many failed contractors broke.
The operating line of credit
An operating line, or revolving credit facility, lets the contractor borrow and repay as needed up to a limit, paying interest only on what is drawn. It is meant to smooth the timing differences in the operating cycle: drawing when payroll and suppliers are due before owner payments arrive, and repaying when they do. A line that is fully drawn for months at a time is no longer bridging timing; it is funding a permanent shortfall, and lenders and sureties will notice.
Banks usually limit the amount available under the line to a borrowing base calculated from the contractor's receivables. Only eligible receivables count, and each type is margined at a percentage.
| Borrowing base item | Typical treatment (illustrative) |
|---|---|
| Progress receivables under 90 days from creditworthy owners | Eligible; margined at about 75 % |
| Receivables over 90 days | Ineligible |
| Holdback receivable | Often ineligible, or margined at a low rate, because the bank's claim ranks behind statutory trusts and lien rights |
| Receivables from related parties or in dispute | Ineligible |
| Receivables from jobs where the bank's security may be subordinate to trust claims or bonds | May be excluded or reduced |
| Priority payables, such as unremitted payroll deductions and sales taxes | Deducted from the base as potential prior claims |
# Borrowing base for Kestrel at month-end (illustrative)
receivables_by_age = {"current": 3_560_000, "31-60": 1_970_000, "61-90": 900_000, "over 90": 470_000}
disputed = 380_000            # included in the 61-90 bucket
holdback = 2_700_000
priority_payables = 210_000   # government remittances due
eligible = sum(v for k, v in receivables_by_age.items() if k != "over 90") - disputed
base = 0.75 * eligible + 0.0 * holdback - priority_payables
limit = 4_000_000
print(f"Eligible receivables: {eligible:,}")
print(f"Borrowing base: {base:,.0f}; line limit {limit:,}; "
f"available {min(base, limit):,.0f}")Eligible receivables: 6,050,000 Borrowing base: 4,327,500; line limit 4,000,000; available 4,000,000
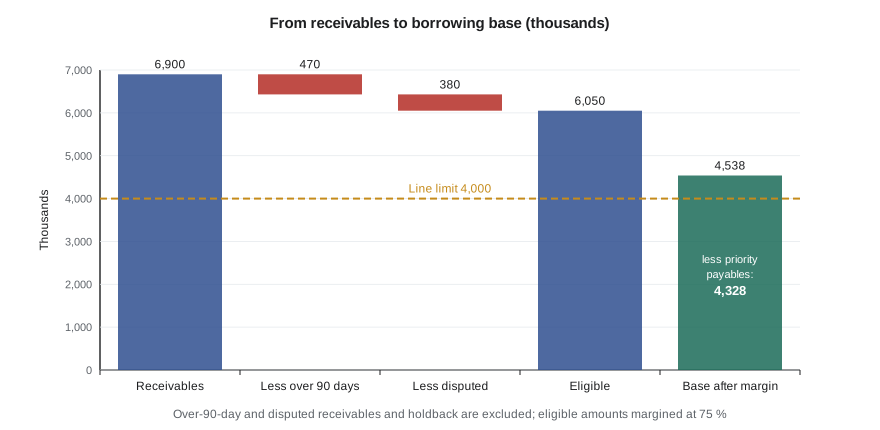
Kestrel's line has a $4 million limit, but on this month's receivables the margin formula gives a borrowing base of about $4.3 million, so the full limit can be used. If receivables aged or a large owner disputed a claim, the borrowing base could shrink below the limit at exactly the moment the firm most needs cash.
Worked problem
Interest on a fluctuating line
Kestrel draws on its line during a three-month period: $0 in October, an average of $1,200,000 in November and $2,100,000 in December. The rate is prime plus 1.25 %, with prime at 5.0 % (illustrative). There is a standby fee of 0.25 % a year on the undrawn part of the $4,000,000 limit. What is the cost for the quarter?
Show solution
- Interest rate = 6.25 % a year. Interest: November 1,200,000 × 6.25 % × 30/365 = $6,164; December 2,100,000 × 6.25 % × 31/365 = $11,147; October $0. Total $17,311.
- Undrawn amounts: October $4,000,000 for 31 days, November $2,800,000 for 30 days, December $1,900,000 for 31 days.
- Standby fee = 0.25 % × (4,000,000 × 31 + 2,800,000 × 30 + 1,900,000 × 31) ÷ 365 = 0.0025 × 731,233 = $1,828.
- Total cost = 17,311 + 1,828 = $19,139.
Answer: The quarter's financing cost is a little over $19,000, small compared with the payroll and supplier payments it supported. The bigger question for management is why the line was needed and whether December's draw will be repaid when January's receipts arrive.
Covenants and reporting
Loan agreements include covenants: promises the borrower makes about its financial condition and conduct. Breaching a covenant gives the lender the right to demand repayment, raise the rate or impose conditions, even if every payment has been made on time. Contractors should know their covenants, test them each month, and talk to the bank before a breach rather than after.
| Typical covenant | Example threshold (illustrative) | Kestrel at year-end |
|---|---|---|
| Minimum working capital | At least $2,000,000 | $2,450,000 |
| Minimum current ratio | At least 1.15 | 1.21 |
| Maximum debt to tangible net worth | No more than 3.5 : 1 | 2.9 : 1 |
| Minimum debt service coverage | Cash flow before interest at least 1.25 times principal and interest | About 4.5 times |
| Limits on dividends and shareholder loans | Not without lender consent if ratios would fall below thresholds | Complied |
| Reporting | Monthly borrowing base, quarterly WIP schedule, annual reviewed statements within 120 days | Complied |
liab, equity, intangibles = 12_750_000, 4_400_000, 0
cash_flow = 1_230_000 + 620_000 + 140_000 + 330_000   # net income + depreciation + interest + tax
debt_service = 380_000 + 140_000                      # principal repaid + interest
print(f"Debt to tangible net worth: {liab / (equity - intangibles):.2f}")
print(f"Debt service coverage: {cash_flow / debt_service:.2f}")Debt to tangible net worth: 2.90 Debt service coverage: 4.46
The debt service coverage here uses a simple measure of cash flow, earnings before interest, tax, depreciation and amortization (EBITDA); banks define it precisely in each agreement, and some deduct taxes, dividends or maintenance capital spending. Total liabilities to equity is high for Kestrel at 2.9 times, but typical for a general contractor whose liabilities are mostly payables to subcontractors.
Term loans and equipment financing
A term loan is repaid over a fixed period, usually in equal monthly payments of principal and interest. Contractors use term loans for equipment, yards and buildings, and sometimes to convert a chronically drawn operating line into permanent financing. Equipment loans are usually secured on the equipment, with terms matched to its life and a down payment of 10 to 25 %. The payment on an amortizing loan is found with the annuity formula.
def payment(principal, annual_rate, years, per_year=12):
    r, n = annual_rate / per_year, years * per_year
    return principal * r / (1 - (1 + r) ** -n)
principal, rate, years = 350_000, 0.068, 5
pmt = payment(principal, rate, years)
bal, first_year_principal = principal, 0
for m in range(12):
    interest = bal * rate / 12
    first_year_principal += pmt - interest
    bal -= pmt - interest
print(f"Monthly payment: {pmt:,.2f}")
print(f"Principal repaid in year 1 (current portion): {first_year_principal:,.0f}")
print(f"Balance after one year: {bal:,.0f}")
print(f"Total interest over the loan: {pmt * years * 12 - principal:,.0f}")Monthly payment: 6,897.44 Principal repaid in year 1 (current portion): 60,842 Balance after one year: 289,158 Total interest over the loan: 63,846
On the balance sheet, the principal due in the next twelve months is a current liability and the rest is long-term. That split is why a five-year equipment loan affects working capital far less than paying cash or drawing on the line: only about $61,000 of the $350,000 loan reduces working capital in the first year.
Leasing
A lease gives the contractor the right to use an asset for a period in return for payments. Contractors lease equipment, vehicles, office space and yards. Leases can be short-term rentals, long-term operating leases that return the asset at the end, or finance leases that transfer most of the risks and rewards of ownership and often end with a purchase option. The accounting depends on the framework, and it affects how the lease looks to a surety.
| Framework | Lessee accounting | Effect on contractor's balance sheet |
|---|---|---|
| ASPE (Section 3065) | Capital leases, which transfer substantially all benefits and risks, are recorded as an asset and an obligation; operating leases are expensed as payments are made | Operating leases stay off the balance sheet; capital leases add debt |
| IFRS 16 | Almost all leases over 12 months are recorded as a right-of-use asset and a lease liability, except low-value assets | Most leases add assets and liabilities; current portion reduces working capital |
| Short-term rentals (12 months or less) | Expensed as incurred under all frameworks if the exemption is elected | No balance sheet effect |
Sureties look through the accounting label. Whether or not a lease appears on the balance sheet, a contractor that has committed to five years of equipment payments has a fixed obligation. Many surety analysts add the next year's lease payments to current liabilities, or capitalize long-term leases, when they assess working capital and leverage, so that firms that lease and firms that borrow are compared on the same basis.
Worked problem
Lease or buy with a loan
Kestrel needs a $240,000 track loader for five years. Option A: buy with a five-year loan at 6.8 %, expecting to sell the loader for $80,000 at the end. Option B: a five-year lease at $4,250 a month with no purchase option; maintenance is the same either way. Ignoring tax, which costs less in present value terms at a discount rate of 7 %?
Show solution
- Option A: the present value of the loan payments equals the $240,000 borrowed (at a rate close to the discount rate), less the present value of the $80,000 resale: 80,000 ÷ 1.07^5 = $57,040. Net present cost ≈ 240,000 − 57,040 = $182,960.
- Option B: present value of 60 payments of $4,250 at 7 % a year (0.583 % a month) = 4,250 × [1 − 1.00583^−60] ÷ 0.00583 = 4,250 × 50.50 = $214,600.
- Difference ≈ $31,600 in favour of buying.
Answer: Buying is cheaper here because Kestrel keeps the residual value. Leasing might still be chosen if the firm wants to preserve borrowing capacity, avoid residual value risk or keep a newer fleet, but the comparison should include tax effects and how each option looks to the surety.
def pv_annuity(pmt, annual_rate, months):
    r = annual_rate / 12
    return pmt * (1 - (1 + r) ** -months) / r
buy = 240_000 - 80_000 / 1.07 ** 5
lease = pv_annuity(4_250, 0.07, 60)
print(f"Buy with loan, net present cost: {buy:,.0f}")
print(f"Lease, present cost:             {lease:,.0f}")
print(f"Advantage of buying: {lease - buy:,.0f}")Buy with loan, net present cost: 182,961 Lease, present cost: 214,633 Advantage of buying: 31,672
Owners' money: equity, shareholder loans and dividends
For a private contractor, the owners are often the most important source of financing. Every dollar of profit left in the business adds to equity and working capital. Many owners take money out of the business through salaries, bonuses and dividends in a way that minimizes their personal tax, and sometimes lend it back as shareholder loans. Sureties and banks pay close attention to these flows.
| Owner transaction | How sureties and banks usually view it |
|---|---|
| Retaining profits in the company | Strongly positive; the main way bonding capacity grows |
| Large year-end bonuses or dividends | Reduces equity and working capital; may breach covenants |
| Loans from shareholders to the company | Treated as equity only if formally subordinated to the surety and postponed in favour of the bank |
| Loans from the company to shareholders or affiliates | Usually deducted from working capital and often from equity, as they may not be collected |
| Personal guarantees and indemnities | Expected for private contractors; the owners' personal net worth supports the company's credit (Lesson 11) |
Worked problem
Bonus versus retained profit
Before year-end, Kestrel's owners consider paying themselves a $600,000 bonus, which would be deductible to the company and reduce its income tax by about $130,000. What happens to working capital and equity compared with not paying it?
Show solution
- Without the bonus: tax on the extra income is about $130,000; equity and working capital rise by 600,000 − 130,000 = $470,000 more than with the bonus.
- With the bonus: cash falls by $600,000, partly offset by $130,000 less tax; working capital and equity are about $470,000 lower.
- Working capital would fall from $2,450,000 toward about $1,980,000, below the bank's $2,000,000 covenant.
Answer: The bonus might suit the owners' personal tax planning but would breach a covenant and reduce bonding capacity. A common compromise is to pay the bonus and lend most of it back as a subordinated, postponed shareholder loan, which the surety and bank treat as equity.
Choosing the right mix
There is no single right capital structure for a contractor, but a few principles hold. Fund permanent needs, such as equipment and the base level of working capital, with equity and long-term debt. Use the operating line for genuine timing swings. Keep enough unused borrowing capacity to absorb a bad month. Match equipment financing to equipment life. Watch how each decision affects working capital and equity, because those decide bonding capacity. And talk to the surety and bank early about plans for growth, large equipment purchases or owner distributions, so that the financing is in place before it is needed.
Common mistakes
MistakeUsing the operating line to buy equipment or cover losses.
InsteadFund long-lived assets with term debt or equity; the line is for timing swings.
MistakeAssuming the full line limit is always available.
InsteadAvailability depends on the borrowing base, which shrinks when receivables age or are disputed.
MistakeDiscovering a covenant breach when the year-end statements arrive.
InsteadTest covenants monthly and talk to the bank before a breach.
MistakeBelieving off-balance-sheet leases are invisible to sureties.
InsteadSureties add lease commitments back when assessing working capital and leverage.
MistakeComparing lease and buy by monthly payment alone.
InsteadCompare present values, including residual value, tax and the effect on working capital.
MistakePaying large year-end bonuses without considering covenants and bonding.
InsteadModel the effect on working capital and equity; consider subordinated shareholder loans.
Summary and key terms
- Contractors finance themselves with retained earnings, owner equity and loans, operating lines, term loans, leases and supplier credit.
- Match financing to the use: lines for timing swings, term debt and equity for equipment and permanent working capital.
- Operating lines are limited by a borrowing base of eligible receivables margined at a percentage.
- Covenants on working capital, current ratio, leverage and debt service must be tested monthly.
- Term loan payments follow the annuity formula; only the current portion reduces working capital.
- Under ASPE, operating leases stay off the balance sheet and capital leases are recorded; IFRS 16 records most leases; sureties look through the labels.
- Owner bonuses, dividends and loans have a large effect on working capital, equity and bonding.
- Operating line of credit
- A revolving facility for short-term borrowing up to a limit.
- Borrowing base
- The amount available under a line, based on margined eligible receivables.
- Margin rate
- The percentage of eligible collateral a lender will advance against.
- Covenant
- A borrower's promise in a loan agreement about financial condition or conduct.
- Term loan
- A loan repaid over a fixed period, usually in instalments.
- Current portion of long-term debt
- Principal due within the next twelve months.
- Right-of-use asset
- A lessee's asset representing its right to use a leased item.
- Lease liability
- The present value of a lessee's remaining lease payments.
- Subordination
- An agreement that a debt ranks behind another creditor's claims.
- Debt service coverage
- Cash flow available divided by principal and interest payments due.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Why should equipment not be bought with the operating line?
Show answer
Line draws are current liabilities, so working capital falls as if cash were used; long-lived assets should be funded long term.
Eligible receivables are $5,000,000 at a 75 % margin and priority payables are $150,000. What is the borrowing base?
Show answer
$3,600,000.
Name three common bank covenants.
Show answer
Minimum working capital, minimum current ratio, maximum debt to tangible net worth, minimum debt service coverage.
What is the monthly payment on $100,000 over 5 years at 6 % a year?
Show answer
About $1,933.
Why does a term loan affect working capital less than paying cash?
Show answer
Only the principal due in the next year is a current liability.
How are operating leases treated under ASPE and under IFRS 16?
Show answer
ASPE: expensed, off balance sheet. IFRS 16: right-of-use asset and lease liability on balance sheet.
Why do sureties add back lease commitments?
Show answer
To compare firms that lease and firms that borrow on the same basis.
When will a surety treat a shareholder loan as equity?
Show answer
When it is formally subordinated and postponed.
Why might a bank exclude holdback from the borrowing base?
Show answer
Collection depends on completion and close-out, and statutory trusts or lien rights may rank ahead.
Give one reason to lease rather than buy even if leasing costs more.
Show answer
Preserve borrowing capacity, avoid residual value risk or keep a newer fleet.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.