
ECON-101 · Lesson 12 of 12 · 31 min
Externalities, public goods and factor markets
Lesson 5 listed the main reasons markets can fail. This final lesson examines two of them in depth, externalities and public goods, and the policies used to address them, including the carbon pricing debates of recent years. It then turns to factor markets, the markets for labour, capital and land, where households sell the resources they own and firms buy them. Factor markets determine wages and incomes, and they connect microeconomics to the questions of income distribution and inequality that ECON-102 takes up. The lesson closes with a short review of the course's main ideas.
Externalities
An externality is a cost or benefit of an activity that falls on people who are not party to the transaction and is not reflected in the price. A negative externality imposes costs on others: a factory's emissions harm the health of nearby residents, traffic congestion slows other drivers, and greenhouse gas emissions contribute to climate change that affects everyone. A positive externality confers benefits on others: a vaccinated person reduces the risk of infection for others, a homeowner who maintains an attractive garden raises neighbours' property values, and basic research produces knowledge that many firms use.
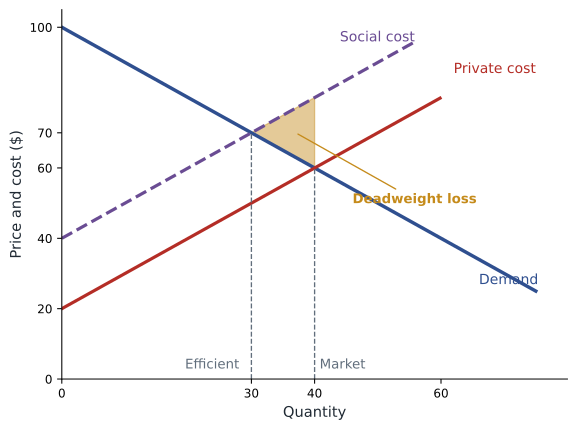
With a negative externality, the market supply curve reflects only the private costs of producers, not the external costs. The social cost of production, private plus external cost, is higher. The market therefore produces more than the socially efficient quantity, where the value to buyers equals the full social cost. With a positive externality, the market demand curve reflects only private benefits, so the market produces less than the efficient quantity. In both cases, there is a deadweight loss compared with the efficient outcome.
Correcting externalities
Governments use several approaches. Command-and-control regulation sets standards directly: limits on emissions from vehicles and power plants, bans on certain chemicals, requirements to install scrubbers. Regulation is clear and enforceable but can be costly, because it does not let firms that can cut pollution cheaply do more of the work. Market-based policies use prices. A Pigouvian tax equal to the marginal external cost makes producers take account of the harm they cause, shifting the private supply curve up to the social cost curve and moving output to the efficient level. A cap-and-trade system sets a total limit on emissions and issues tradable permits; firms that can cut emissions cheaply sell permits to firms for which cutting is expensive, so the cap is met at the lowest total cost. Subsidies can encourage activities with positive externalities, such as vaccinations, research and education.
Worked problem
A Pigouvian tax
In a market for a chemical, demand is \( P = 100 - Q \), private marginal cost is \( MC = 20 + Q \), and each unit causes $20 of pollution damage to nearby residents. Find the market quantity, the efficient quantity, the deadweight loss of the externality, and the tax that would achieve efficiency.
Show solution
- Market: \( 100 - Q = 20 + Q \), so Q = 40 and P = $60.
- Social cost: \( MSC = 40 + Q \). Efficient: \( 100 - Q = 40 + Q \), so Q = 30 and P = $70.
- Deadweight loss = ½ × (40 − 30) × $20 = $100.
- A tax of $20 per unit raises private cost to \( 40 + Q \) and moves output to the efficient 30 units.
Answer: The market overproduces by 10 units; a $20 tax equal to the marginal damage restores efficiency and raises $600 of revenue that can be returned to residents or used to cut other taxes.
# Market vs efficient output with a negative externality, and the effect of a Pigouvian tax
def solve(intercept_d, slope_d, intercept_s, slope_s):
    q = (intercept_d - intercept_s) / (slope_d + slope_s)
    return q, intercept_d - slope_d * q
damage = 20                              # external cost per unit, $
q_m, p_m = solve(100, 1, 20, 1)          # demand P = 100 - Q, private MC = 20 + Q
q_e, p_e = solve(100, 1, 20 + damage, 1) # social MC = 40 + Q
print(f"market:    Q = {q_m:.0f}, P = ${p_m:.0f}")
print(f"efficient: Q = {q_e:.0f}, P = ${p_e:.0f}")
print(f"deadweight loss of the externality: ${0.5 * (q_m - q_e) * damage:.0f}")
for tax in (0, 10, 20, 30):
    q_t, _ = solve(100, 1, 20 + tax, 1)
    net = sum((100 - q) - (20 + q) - damage for q in [x / 100 for x in range(int(q_t * 100))]) / 100
print(f"tax ${tax:2}: output {q_t:.0f}, net social surplus ${net:,.0f}")market: Q = 40, P = $60 efficient: Q = 30, P = $70 deadweight loss of the externality: $100 tax $ 0: output 40, net social surplus $800 tax $10: output 35, net social surplus $875 tax $20: output 30, net social surplus $900 tax $30: output 25, net social surplus $875
The output shows that net social surplus, the value to buyers minus private and external costs, is highest when the tax equals the marginal damage of $20. A smaller tax leaves too much output; a larger tax cuts output below the efficient level. In practice, estimating the marginal damage is the hard part. For greenhouse gases, governments use estimates of the social cost of carbon, the present value of future damages from one more tonne of carbon dioxide, which vary widely depending on assumptions about climate impacts and discount rates.
Carbon pricing in practice
Canada introduced a national minimum carbon price in 2019, applying either provincial systems or a federal backstop consisting of a fuel charge on consumers and an output-based pricing system for large industrial emitters. Most fuel charge revenue was returned to households as rebates. The consumer fuel charge became politically contentious amid concerns about affordability, and the federal government set it to zero on 1 April 2025, ending the rebates. Carbon pricing for large industrial emitters continued under federal and provincial output-based systems, which charge facilities for emissions above an output-based benchmark while protecting competitiveness; a federal review of the benchmark was under way in 2026. Supporters of the consumer charge argued that it cut emissions at low cost and that rebates left most lower-income households better off; opponents argued that it raised living costs and that regulation and subsidies were more acceptable. The industrial system is generally seen by economists as the more cost-effective part of the policy, though its effectiveness depends on credit prices, which in 2025 and 2026 traded well below the headline price in some provinces.
The Coase theorem
Not every externality requires government action. Ronald Coase argued in 1960 that if property rights are clearly defined and the costs of bargaining are low, the people affected by an externality can negotiate an efficient outcome themselves, whoever initially holds the rights. If a farmer has the right to clean water, a factory that pollutes it can pay her to accept some pollution if that is worth more to the factory than the harm to her. If the factory has the right to pollute, the farmer can pay it to cut back. Either way, the efficient level of pollution results; only the distribution of income differs. The Coase theorem explains private solutions such as easements, neighbour agreements and conservation purchases. But it rarely applies to large-scale problems, where many people are affected, bargaining costs are high and free riding is tempting, which is why climate change and urban air pollution require collective action.
Public goods and common resources
Economists classify goods by two characteristics. A good is excludable if people who do not pay can be prevented from using it. A good is rival if one person's use reduces the amount available to others. Private goods, such as a sandwich, are both excludable and rival. Public goods are neither: national defence, flood control, street lighting and the knowledge produced by basic research benefit everyone, and one person's benefit does not reduce another's. Because people cannot be excluded, each has an incentive to free ride, enjoying the benefit without paying, so private markets underprovide public goods. Governments therefore provide them, financed by taxes, deciding how much to provide using cost-benefit analysis.
| Rival | Non-rival | |
|---|---|---|
| Excludable | Private goods: food, clothing, cars | Club goods: streaming services, toll roads without congestion, private parks |
| Non-excludable | Common resources: ocean fish, groundwater, congested free roads | Public goods: national defence, flood control, basic research |
Common resources are rival but not excludable, which creates the tragedy of the commons described by Garrett Hardin: each user has an incentive to use as much as possible, because the cost of depletion is shared by all, so the resource is overused. The collapse of the northern cod fishery off Newfoundland and Labrador, which led to a federal moratorium in 1992 and the loss of tens of thousands of jobs, is a stark example; overfishing of many US stocks led to rebuilding plans under the Magnuson–Stevens Act. Solutions include quotas and licences, individual transferable quotas that give fishers a stake in conservation, property rights, and community management, which Elinor Ostrom showed can work well when users can monitor one another and set their own rules.
Factor markets: the demand for labour
The prices of labour, capital and land are determined in factor markets by supply and demand, like other prices. But the demand for a factor is a derived demand: firms want workers not for their own sake but for the output they produce. A profit-maximizing firm hires workers up to the point where the extra revenue from the last worker equals the wage. The extra revenue is the marginal revenue product of labour (MRP), which for a firm selling in a competitive market equals the marginal product of labour times the price of the output. Because of diminishing marginal returns (lesson 8), MRP falls as more workers are hired, so the labour demand curve slopes downward.
# Hiring decision: hire workers while marginal revenue product is at least the wage
marginal_product = [40, 60, 50, 35, 25, 15, 5]   # pizzas per day from each extra worker (lesson 8)
price = 6.0                                       # $ per pizza
for wage in (160, 120, 220):
    hired = 0
    for mp in marginal_product:
        if mp * price >= wage:
            hired += 1
        else:
            break
print(f"daily wage ${wage}: hire {hired} workers; MRP of last hired = ${marginal_product[hired - 1] * price:.0f}")daily wage $160: hire 4 workers; MRP of last hired = $210 daily wage $120: hire 5 workers; MRP of last hired = $150 daily wage $220: hire 3 workers; MRP of last hired = $300
The labour demand curve shifts when output prices change (higher pizza prices raise MRP), when productivity changes (better ovens raise marginal product), and when the prices of other inputs change. Technology can either complement workers, raising their productivity and demand, or substitute for them, as when automation replaces routine tasks. Much recent research on artificial intelligence asks which tasks it will complement and which it will replace.
Labour supply, wages and monopsony
The supply of labour reflects people's choices between work and other uses of time. A higher wage makes leisure more costly (a substitution effect that encourages more work) but also makes people richer (an income effect that may encourage less work), so individual labour supply can even bend backward at high wages. For a market as a whole, higher wages draw in more workers from other occupations and regions, so market labour supply slopes upward. In competitive labour markets, wages equal the value of workers' marginal product, which helps explain why wages differ: workers with more human capital, in occupations with higher productivity or in jobs that are dangerous or unpleasant (compensating differentials) tend to earn more. Discrimination, unions and differences in bargaining power also affect wages.
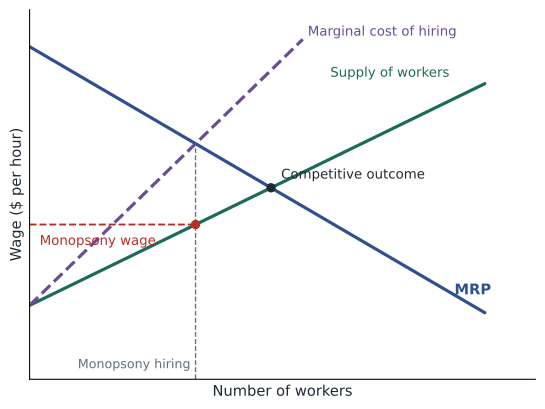
A monopsony is a market with a single buyer, and in labour markets it describes an employer with power to set wages, because workers have few alternative employers nearby or find it costly to switch jobs. A monopsonist pays less than the value of workers' marginal product and hires fewer workers than a competitive market would. Classic examples are mining towns and remote hospitals; modern research finds that many labour markets are concentrated enough to give employers some wage-setting power. This is the theoretical reason, mentioned in lesson 6, why a moderate minimum wage can raise both wages and employment: by setting a wage floor closer to the competitive wage, it removes the employer's incentive to restrict hiring. Unions can play a similar countervailing role, while also, in other settings, raising wages above competitive levels.
Worked problem
Wage differences and human capital
An electrician's apprenticeship takes four years, during which an apprentice earns $25,000 a year less than a general labourer. After certification, an electrician earns $22,000 a year more than a labourer for 30 years. Ignoring discounting, is the training worthwhile? How does discounting change the comparison?
Show solution
- Cost: 4 × $25,000 = $100,000 of forgone earnings.
- Benefit: 30 × $22,000 = $660,000 of extra earnings.
- Without discounting, the benefit is 6.6 times the cost.
- With discounting (BUS-110 lesson 10), later earnings count for less, but at any reasonable rate the benefit still far exceeds the cost.
Answer: Training is worthwhile on these illustrative numbers, which helps explain why skilled trades command higher wages: workers must be compensated for the cost of acquiring human capital. A shortage of skilled trades would show up as rising wages that attract more apprentices over time.
Capital, land and the distribution of income
The markets for capital and land work similarly. Firms rent or buy capital up to the point where its marginal revenue product equals its cost, which depends on interest rates, a link to the macroeconomics of ECON-102. Land is fixed in supply, so its rent is determined mainly by demand, which is why land in city centres is so expensive and why economists from Henry George onward have argued that taxes on land value cause little distortion. Together, factor markets determine the functional distribution of income among wages, interest, rent and profit, and, combined with who owns which factors, the personal distribution of income among households. Why incomes have become more unequal in many countries since 1980, and what policies might respond, are central questions of ECON-102.
Looking back
This course has built a toolkit for thinking about choices and markets. Opportunity cost and marginal thinking guide individual decisions. Comparative advantage explains why specialization and trade raise living standards. Supply and demand, with elasticity, predict how prices and quantities respond to events and policies. Surplus analysis shows when markets are efficient and measures the cost of distortions. The theory of the firm explains costs, competition, monopoly and strategic behaviour. And the analysis of market failure identifies where well-designed public policy can improve on market outcomes, and where it may do more harm than good. These tools are used every day by businesses setting prices, governments designing taxes and regulations, and citizens weighing policy proposals.
Common mistakes
MistakeExternalities only arise from pollution.
InsteadExternalities include congestion, noise, vaccination, research spillovers and many other effects on third parties.
MistakeThe efficient level of pollution is zero.
InsteadThe efficient level is where the marginal benefit of the activity equals its marginal social cost, which is usually above zero.
MistakePublic goods are anything provided by government.
InsteadPublic goods are non-rival and non-excludable; governments also provide many private goods, and some public goods are provided privately.
MistakeFirms hire workers until wages are as low as possible.
InsteadFirms hire until the marginal revenue product of labour equals the wage.
MistakeA minimum wage always reduces employment.
InsteadIn a monopsony labour market, a moderate minimum wage can raise both wages and employment.
Summary and key terms
- Externalities are costs or benefits borne by third parties; negative externalities lead to overproduction and positive ones to underproduction.
- Regulation, Pigouvian taxes, cap-and-trade and subsidies can correct externalities; market-based tools minimize the cost of reaching a target.
- Carbon pricing is economically efficient in principle but politically contested; Canada removed its consumer charge in 2025 and kept industrial pricing, while the United States relies mainly on regulation, subsidies and state cap-and-trade.
- The Coase theorem shows private bargaining can solve externalities when property rights are clear and bargaining costs are low.
- Public goods are non-rival and non-excludable, so free riding leads to underprovision; common resources are overused.
- Labour demand is derived demand; firms hire until marginal revenue product equals the wage.
- Wages reflect productivity, human capital, compensating differentials and bargaining power.
- Monopsony lets employers pay below marginal revenue product; minimum wages and unions can counter it.
- Externality
- A cost or benefit of an activity that falls on third parties and is not reflected in prices.
- Marginal social cost
- The sum of marginal private cost and marginal external cost.
- Pigouvian tax
- A tax equal to the marginal external cost of an activity.
- Cap-and-trade
- A system that limits total emissions and allows trading of emission permits.
- Coase theorem
- The idea that private bargaining can achieve efficiency if property rights are clear and bargaining costs are low.
- Public good
- A good that is non-rival and non-excludable.
- Free rider
- Someone who benefits from a good without paying for it.
- Tragedy of the commons
- The overuse of a common resource because individuals do not bear the full cost of depletion.
- Marginal revenue product
- The extra revenue from employing one more unit of a factor.
- Monopsony
- A market with a single buyer, such as a dominant employer.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Give one example each of a negative and a positive externality.
Show answer
Negative: pollution or congestion. Positive: vaccination or research spillovers.
Why does a negative externality lead to overproduction?
Show answer
Producers ignore external costs, so private supply lies below social cost.
Demand P = 80 − Q, private MC = 10 + Q, damage $10 per unit. Market and efficient quantities?
Show answer
Market Q = 35; efficient Q = 30.
What tax corrects the externality in the previous question?
Show answer
$10 per unit.
State the Coase theorem and one reason it often fails.
Show answer
Bargaining can achieve efficiency with clear rights and low costs; it fails when many parties and high bargaining costs exist.
Classify a public library's quiet reading room at a busy time.
Show answer
Rival and largely non-excludable: close to a common resource; when uncrowded, close to a public good.
Why did the northern cod fishery collapse?
Show answer
Open access led to overfishing, a tragedy of the commons.
A worker adds 20 units a day; output sells for $9. Should she be hired at a wage of $170?
Show answer
Yes, MRP = $180 exceeds the wage.
Why might a moderate minimum wage raise employment in a monopsony?
Show answer
It removes the employer's incentive to restrict hiring to keep wages low.
Portfolio task: choose a local externality, such as noise or congestion, and propose a policy to address it, explaining its costs and benefits.
Show answer
Answers vary; should compare regulation, pricing and bargaining options.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.