
ACCT-101 · Lesson 4 of 12 · 31 min
The trial balance and finding errors
Once a period's journal entries have been posted, the bookkeeper prepares a trial balance: a list of every account in the ledger with its debit or credit balance, and totals of the two columns. If the totals agree, the ledger is at least arithmetically in balance. If they disagree, there is an error somewhere, and the trial balance is the first tool for finding it. This lesson builds the May trial balance for Birchwood Bikes, explains what a trial balance proves and what it cannot prove, shows practical techniques for locating errors, and explains how to correct errors with correcting entries rather than by erasing or overwriting records.
Preparing a trial balance
A trial balance lists accounts in chart-of-accounts order (assets, liabilities, equity, revenues, expenses), with each balance in the debit or credit column according to the side on which it falls. It is dated at a point in time, usually the end of a month or year. The trial balance prepared directly from the ledger before any end-of-period adjustments is the unadjusted trial balance; lesson 6 prepares the adjusted trial balance, and lesson 7 the post-closing trial balance.
| Account | Debit | Credit |
|---|---|---|
| Cash | 37,800 | |
| Accounts receivable | 1,000 | |
| Supplies | 1,500 | |
| Prepaid insurance | 3,600 | |
| Equipment | 18,000 | |
| Accounts payable | 850 | |
| Note payable | 20,000 | |
| Share capital | 40,000 | |
| Dividends | 500 | |
| Service revenue | 7,000 | |
| Rent expense | 2,000 | |
| Wages expense | 3,100 | |
| Utilities expense | 350 | |
| Totals | 67,850 | 67,850 |
The totals agree at $67,850. Note that the trial balance total is not the same as total assets ($61,900). It includes revenues, expenses and dividends, which have not yet been closed into retained earnings, so it is simply the sum of all debit balances and, separately, of all credit balances. Note too that dividends sit in the debit column alongside expenses, because they reduce equity, but they will appear on the statement of changes in equity, not on the income statement.
# Build a trial balance from ledger balances and check it (illustrative)
balances = {   # account: (balance, normal side)
    "Cash": (37800, "Dr"), "Accounts receivable": (1000, "Dr"),
    "Supplies": (1500, "Dr"), "Prepaid insurance": (3600, "Dr"),
    "Equipment": (18000, "Dr"), "Accounts payable": (850, "Cr"),
    "Note payable": (20000, "Cr"), "Share capital": (40000, "Cr"),
    "Dividends": (500, "Dr"), "Service revenue": (7000, "Cr"),
    "Rent expense": (2000, "Dr"), "Wages expense": (3100, "Dr"),
    "Utilities expense": (350, "Dr"),
}
dr = sum(b for b, s in balances.values() if s == "Dr")
cr = sum(b for b, s in balances.values() if s == "Cr")
for acct, (b, s) in balances.items():
    print(f"{acct:<22}{b if s == 'Dr' else '':>9}{b if s == 'Cr' else '':>9}")
print(f"{'Totals':<22}{dr:>9,}{cr:>9,}")
print("In balance" if dr == cr else f"Out by {abs(dr - cr):,}")Cash 37800 Accounts receivable 1000 Supplies 1500 Prepaid insurance 3600 Equipment 18000 Accounts payable 850 Note payable 20000 Share capital 40000 Dividends 500 Service revenue 7000 Rent expense 2000 Wages expense 3100 Utilities expense 350 Totals 67,850 67,850 In balance
What a trial balance proves, and what it does not
A trial balance in balance shows that, for the entries posted, total debits equal total credits and the arithmetic of the balances is correct. It does not show that every transaction was recorded, that the right accounts were used, or that the amounts are right. Several kinds of error leave the trial balance in balance: a transaction never recorded at all; a transaction recorded twice; an entry posted to the wrong account on the correct side, such as rent recorded as wages; an entry with the wrong amount on both sides; and offsetting errors that happen to cancel. These are found by other means, such as bank reconciliations (lesson 10), customer and supplier statements, review of unusual balances, and analytical comparison with prior months or budgets.
| Error | Trial balance still balances? | How it is usually found |
|---|---|---|
| Transaction omitted entirely | Yes | Missing invoice sequence, bank reconciliation, supplier statement |
| Transaction recorded twice | Yes | Duplicate document numbers, bank reconciliation, customer complaint |
| Wrong account, correct side (rent as wages) | Yes | Review of account detail, budget comparison |
| Wrong amount on both sides ($540 entered as $450) | Yes | Comparing entries with source documents |
| Debit posted as a credit (or vice versa) | No; out by twice the amount | Divide the difference by 2 and look for that amount |
| One side of an entry not posted | No; out by the amount | Look for an entry of that amount |
| Transposition (5,400 written as 4,500) | No; difference divisible by 9 | Divide the difference by 9 |
| Slide (5,400 written as 540) | No; difference divisible by 9 | Look for a decimal or zero error |
| Addition error in an account or the trial balance | No | Re-add columns and account balances |
Locating errors when the totals disagree
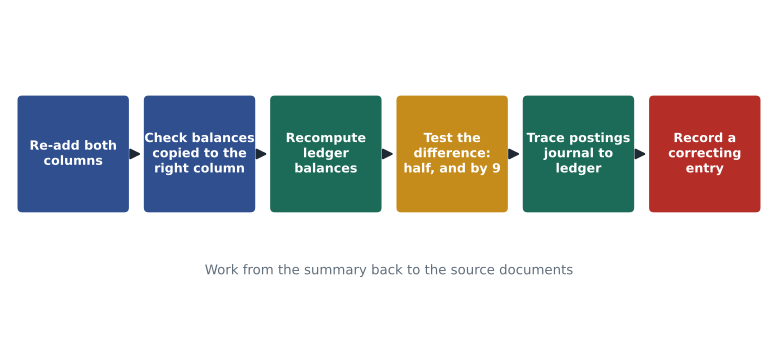
When the columns do not agree, work systematically from the summary back to the source. First re-add both columns of the trial balance. Then check that each balance was copied correctly from the ledger and placed in the right column; a balance in the wrong column produces a difference of twice the amount. Next, recompute each ledger balance. Finally, trace postings from the journal to the ledger, checking that each debit and credit was posted, to the right account, on the right side, and for the right amount.
Three quick tests save time. If the difference is an amount that appears in the records, look for an entry where only one side was posted. If the difference is even, halve it and look for a balance or posting of that amount on the wrong side. If the difference is divisible by 9, suspect a transposition, where two adjacent digits were swapped (for example 72 written as 27, difference 45), or a slide, where a number was written with the decimal point moved (for example 3,100 written as 310, difference 2,790). The divisible-by-9 rule works because swapping two adjacent digits or shifting a number by a power of ten always changes it by a multiple of 9.
# Error-finding hints from a trial balance difference
def hints(diff):
    out = []
    if diff % 2 == 0:
        out.append(f"look for {diff // 2:,} posted on the wrong side")
    if diff % 9 == 0:
        out.append("possible transposition or slide (difference divisible by 9)")
    out.append(f"look for a one-sided posting of {diff:,}")
    return out

for d in (700, 2790, 4500, 63):
    print(d, "->", "; ".join(hints(d)))

# Why transpositions give multiples of 9
for wrong, right in ((5400, 4500), (72, 27), (3100, 310)):
print(right, wrong, abs(wrong - right), abs(wrong - right) % 9 == 0)700 -> look for 350 posted on the wrong side; look for a one-sided posting of 700 2790 -> look for 1,395 posted on the wrong side; possible transposition or slide (difference divisible by 9); look for a one-sided posting of 2,790 4500 -> look for 2,250 posted on the wrong side; possible transposition or slide (difference divisible by 9); look for a one-sided posting of 4,500 63 -> possible transposition or slide (difference divisible by 9); look for a one-sided posting of 63 4500 5400 900 True 27 72 45 True 310 3100 2790 True
Worked problem
Finding the error
A trial balance shows debits of $84,320 and credits of $83,620. The bookkeeper has re-added both columns. What should she look for?
Show solution
- The difference is 84,320 − 83,620 = $700.
- Half the difference is $350. Look for a $350 credit balance listed as a debit, or a $350 credit posting entered as a debit.
- Also look for a $700 credit that was never posted.
- 700 is not divisible by 9, so a transposition is unlikely.
- Suppose she finds that the $350 utility bill was posted as a debit to Accounts payable instead of a credit: accounts payable is understated by $700 relative to the correct figure, and the columns differ by $700.
Answer: Search first for a $350 item on the wrong side; correcting it removes the $700 difference.
Worked problem
A transposition
A ledger shows Wages expense of $3,100, but the trial balance lists it as $1,300. What is the difference and what clue does it give?
Show solution
- The debit column is understated by 3,100 − 1,300 = $1,800.
- 1,800 ÷ 9 = 200 exactly, so the difference is divisible by 9, which points to a transposition or slide.
- Scanning balances for swapped digits finds wages.
Answer: Correct the trial balance listing to $3,100; no journal entry is needed because the ledger itself was right.
Correcting errors
How an error is corrected depends on where it is. If the trial balance was simply copied or added wrongly, fix the trial balance. If a ledger balance was miscalculated, recompute it. If a journal entry or posting is wrong, the professional practice is to leave the original entry in place and record a correcting entry, so that the audit trail shows both the error and its correction. Erasing, overwriting or deleting entries destroys the trail, and in accounting software, posted entries in a closed period are usually locked for exactly this reason.
There are two ways to write a correcting entry. One is to reverse the wrong entry completely and then record the right one. The other, often shorter, is to compare the wrong entry with the correct entry and record only the difference. Both leave the accounts correct; the second uses fewer lines.
Worked problem
A correcting entry
On 12 June, Birchwood Bikes paid $1,200 for a new display rack (equipment) and the bookkeeper recorded: debit Repairs expense 1,200; credit Cash 1,200. The error is found on 30 June. Record the correction.
Show solution
- Correct entry would have been: debit Equipment 1,200; credit Cash 1,200.
- The credit to Cash was right. Only the debit used the wrong account.
- Correcting entry: debit Equipment 1,200; credit Repairs expense 1,200.
- Effect: expense falls by 1,200, so net income rises by 1,200; equipment rises by 1,200.
Answer: Debit Equipment $1,200; credit Repairs expense $1,200.
Worked problem
Correcting a wrong amount
A $2,450 cash sale was recorded as debit Cash 2,540, credit Service revenue 2,540.
Show solution
- Both sides are overstated by 2,540 − 2,450 = $90. The trial balance still balanced.
- Correcting entry: debit Service revenue 90; credit Cash 90.
- Alternatively, reverse the whole entry (debit Service revenue 2,540; credit Cash 2,540) and record the correct one (debit Cash 2,450; credit Service revenue 2,450).
Answer: Debit Service revenue $90; credit Cash $90, or reverse and re-record.
The trial balance in a computerized system
Accounting software will not save an unbalanced entry, so a computerized trial balance always balances. That removes arithmetic and posting errors, but it makes classification errors, omissions and duplicates more important, because the comforting check of an unbalanced trial balance never appears. In practice, bookkeepers review a computerized trial balance by asking whether each balance makes sense: is any asset or expense showing a credit balance, or any liability or revenue a debit balance? Has any account moved sharply compared with last month or last year? Are there accounts with names like 'suspense', 'uncategorized' or 'ask my accountant' that hold unexplained amounts? These reviews are part of the month-end close.
A suspense account is a temporary account sometimes used to hold an amount whose correct account is not yet known, or to make a manual trial balance agree while the error is investigated. It must be cleared to zero before financial statements are issued. A growing suspense balance is a warning sign of weak controls.
Common mistakes
MistakeBelieving a balanced trial balance proves the books are correct.
InsteadIt proves only that debits equal credits for what was posted; omissions, duplicates and misclassifications remain possible.
MistakeTreating the trial balance total as total assets.
InsteadThe trial balance includes revenues, expenses and dividends, so its total is usually larger than total assets.
MistakeErasing or deleting a wrong entry.
InsteadLeave the original and record a correcting entry so the audit trail shows what happened.
MistakeLeaving a balance in a suspense account at year end.
InsteadInvestigate and clear suspense to the correct accounts before issuing statements.
MistakeAssuming software makes error review unnecessary.
InsteadSoftware prevents unbalanced entries but not wrong accounts, wrong amounts, omissions or duplicates.
Summary and key terms
- A trial balance lists every account balance in debit and credit columns at a date.
- Equal totals show arithmetic balance, not correctness.
- Omissions, duplicates, wrong accounts and equal-and-opposite amount errors do not unbalance a trial balance.
- Differences divisible by 2 suggest an item on the wrong side; differences divisible by 9 suggest transpositions or slides.
- Correct posted errors with correcting entries, not by erasing.
- Computerized trial balances always balance, so review balances for reasonableness.
- Suspense accounts are temporary and must be cleared before statements are issued.
- Trial balance
- A list of all ledger accounts and their debit or credit balances at a date, with column totals.
- Unadjusted trial balance
- A trial balance prepared before end-of-period adjusting entries.
- Transposition error
- An error in which two digits are reversed, producing a difference divisible by 9.
- Slide error
- An error in which a decimal point is misplaced, producing a difference divisible by 9.
- Correcting entry
- A journal entry that fixes an earlier error while leaving the original entry in the records.
- Audit trail
- The chain of references linking financial statement amounts to ledger balances, journal entries and source documents.
- Suspense account
- A temporary account holding amounts awaiting classification; it must be cleared to zero.
- Compensating errors
- Two or more errors that offset each other and leave the trial balance in balance.
- Normal balance
- The side on which an account increases; a balance on the other side needs investigation.
- Month-end close
- The routine of reviewing, adjusting and reconciling accounts before issuing period reports.
Practice problems
Work each problem on paper first, then reveal the answer to check.
A trial balance shows debits of $56,200 and credits of $55,300. Suggest two possible errors.
Show answer
A $450 credit posted as a debit (difference 900 = 2 × 450), or a $900 credit not posted; 900 is also divisible by 9, so check for transpositions.
Will recording a $600 purchase of supplies twice unbalance the trial balance?
Show answer
No; both debits and credits are overstated by $600.
Rent of $1,500 was debited to Wages expense. Record the correction.
Show answer
Debit Rent expense 1,500; credit Wages expense 1,500.
$8,200 was written as $2,800 in a ledger. What is the difference and is it divisible by 9?
Show answer
$5,400; yes (5,400 ÷ 9 = 600).
Why is the trial balance total larger than total assets?
Show answer
It includes expenses and dividends on the debit side and revenues on the credit side before closing.
A cash receipt of $750 from a customer on account was not recorded. How would you find it?
Show answer
Bank reconciliation, the customer's remittance advice, or the receivables subledger.
List three questions to ask when reviewing a computerized trial balance.
Show answer
Any balances on the abnormal side? Any large unexplained changes? Any suspense or uncategorized balances?
A $3,000 credit sale was recorded as debit Cash, credit Service revenue. Correct it.
Show answer
Debit Accounts receivable 3,000; credit Cash 3,000.
Explain why deleting a posted entry is bad practice.
Show answer
It destroys the audit trail and can hide errors or fraud; corrections should be visible.
Use the hints function in the Python program for a difference of 1,620. What does it suggest?
Show answer
Look for 810 on the wrong side, a one-sided 1,620 posting, and a possible transposition (1,620 is divisible by 9).
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.