
BUS-110 · Lesson 9 of 12 · 37 min
Loans, mortgages and amortization
Most business and personal loans are repaid by a series of equal payments that cover both interest and principal. Each payment first pays the interest that has built up since the last payment; whatever is left reduces the balance. Over time the balance falls, the interest portion shrinks and the principal portion grows. This process is called amortization, and the table that tracks it payment by payment is an amortization schedule. This lesson applies the annuity formulas from lesson 8 to car loans, business term loans and, most importantly, home mortgages, the largest debt most households ever take on.
The loan payment
A loan is the present value of its payments. Given the amount borrowed (PV), the periodic rate (i) and the number of payments (n), the payment is found with the present value annuity formula rearranged for PMT. For a general annuity, i is the equivalent rate per payment interval.
Worked problem
A car loan
A sales representative finances a $30,000 car at 6.9 % compounded monthly over 5 years. What is the monthly payment, and how much interest will she pay in total?
Show solution
- i = 0.069 ÷ 12 = 0.00575; n = 60.
- PMT = $30,000 × 0.00575 ÷ (1 − 1.00575^−60) = $592.62.
- Total paid = 60 × $592.62 = $35,557.20. Interest = $35,557.20 − $30,000 = $5,557.20.
Answer: The payment is $592.62 a month, and the loan costs about $5,557 in interest.
Amortization schedules
An amortization schedule lists, for every payment, the interest portion (the opening balance times the periodic rate), the principal portion (the payment minus the interest) and the closing balance (the opening balance minus the principal portion). Because the payment is rounded to the cent, the final payment is adjusted so that the balance ends at exactly zero.
Worked problem
A short schedule
A business borrows $6,000 at 9 % compounded monthly and repays it with six monthly payments. Build the amortization schedule.
Show solution
- i = 0.09 ÷ 12 = 0.0075. PMT = $6,000 × 0.0075 ÷ (1 − 1.0075^−6) = $1,026.41.
- Payment 1: interest = $6,000 × 0.0075 = $45.00; principal = $1,026.41 − $45.00 = $981.41; balance = $5,018.59.
- Payment 2: interest = $5,018.59 × 0.0075 = $37.64; principal = $988.77; balance = $4,029.82.
- Continue in the same way; the table below shows every row.
- The final payment is $1,026.42, one cent more than the others, to clear the balance exactly.
Answer: Total interest is $158.47. Note how the interest falls and the principal rises with each payment.
| Payment | Amount | Interest | Principal | Balance |
|---|---|---|---|---|
| 0 | $6,000.00 | |||
| 1 | $1,026.41 | $45.00 | $981.41 | $5,018.59 |
| 2 | $1,026.41 | $37.64 | $988.77 | $4,029.82 |
| 3 | $1,026.41 | $30.22 | $996.19 | $3,033.63 |
| 4 | $1,026.41 | $22.75 | $1,003.66 | $2,029.97 |
| 5 | $1,026.41 | $15.22 | $1,011.19 | $1,018.78 |
| 6 | $1,026.42 | $7.64 | $1,018.78 | $0.00 |
A schedule for a long loan has hundreds of rows, which is why it is almost always built in a spreadsheet. The first row's formulas are written once and filled down: interest = previous balance × rate, principal = payment − interest, balance = previous balance − principal.
The balance at any time
It is often necessary to know the balance partway through a loan, for example when it is to be paid off early, refinanced or renewed. There are two equivalent methods. The prospective method finds the present value of the payments still to come. The retrospective method takes the future value of the original loan and subtracts the future value of the payments already made.
Business term loans
Businesses borrow to buy equipment, vehicles and buildings, or to finance an expansion, usually through a term loan repaid over a fixed number of years. Two repayment structures are common. With blended payments, every payment is the same and the split between interest and principal shifts over time, exactly like a mortgage. With fixed principal payments, the business repays the same amount of principal each period plus the interest on the balance, so the payments start high and fall. Fixed principal loans cost less interest, because the balance falls faster, but they put more strain on cash flow in the early years.
Worked problem
Blended or fixed principal payments?
A manufacturer borrows $120,000 at 8 % compounded monthly, repayable quarterly over 5 years. Compare the first payment and the total interest under blended payments and under fixed principal payments.
Show solution
- Equivalent quarterly rate p = (1 + 0.08 ÷ 12)^3 − 1 = 0.0201336; n = 20.
- Blended: PMT = $120,000 × 0.0201336 ÷ (1 − 1.0201336^−20) = $7,348.27 every quarter. Total interest = 20 × $7,348.27 − $120,000 = $26,965.40.
- Fixed principal: principal = $120,000 ÷ 20 = $6,000 a quarter. First payment = $6,000 + $120,000 × 0.0201336 = $8,416.04; the last is $6,000 + $6,000 × 0.0201336 = $6,120.80.
- Total interest with fixed principal = 0.0201336 × ($120,000 + $114,000 + … + $6,000) = 0.0201336 × $1,260,000 = $25,368.37.
Answer: Fixed principal payments save about $1,597 in interest but require $8,416 in the first quarter instead of $7,348. A business with tight cash flow early on may prefer blended payments.
Mortgages
A Canadian mortgage has two time spans. The amortization period is the time it would take to repay the loan in full, usually 25 years; for insured mortgages, 30 years is allowed for first-time buyers and buyers of newly built homes since December 15, 2024. The term is the length of the current contract, usually 1 to 5 years. At the end of each term the balance is renewed at a new rate, or paid off, or moved to another lender. Under the Interest Act, fixed rates are compounded semi-annually, not in advance, even though payments are monthly or more frequent, so mortgage payments are a general annuity. Variable rates may be compounded monthly; check the contract.
| Feature | Rule at the time of writing (October 2026) |
|---|---|
| Minimum down payment | 5 % of the first $500,000 of the price, 10 % of the portion from $500,000 to $1.5 million; 20 % at $1.5 million or more |
| Mortgage default insurance | Required when the down payment is under 20 %; premium added to the loan |
| Stress test | Qualify at the greater of the contract rate + 2 percentage points or 5.25 % |
| Maximum amortization (insured) | 25 years; 30 years for first-time buyers and new builds |
| Compounding of fixed rates | Semi-annual, under the Interest Act |
| Prepayment | Limited annual prepayment privileges; penalties for breaking a closed term |
Worked problem
The mortgage payment
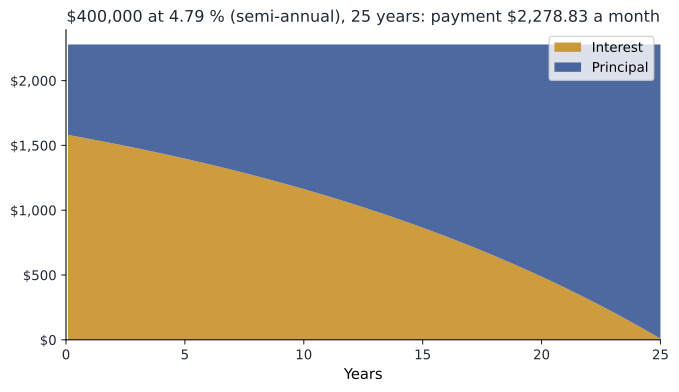
A couple buys a home with a $400,000 mortgage at 4.79 % compounded semi-annually, amortized over 25 years with monthly payments. What is the payment, and how much of the first payment is interest?
Show solution
- Semi-annual rate = 0.0479 ÷ 2 = 0.02395.
- Equivalent monthly rate p = 1.02395^(1/6) − 1 = 0.0039524.
- n = 25 × 12 = 300. PMT = $400,000 × 0.0039524 ÷ (1 − 1.0039524^−300) = $2,278.83.
- First month interest = $400,000 × 0.0039524 = $1,580.96; principal = $2,278.83 − $1,580.96 = $697.87.
Answer: The payment is $2,278.83. Almost 70 % of the first payment is interest.
Worked problem
The balance at renewal
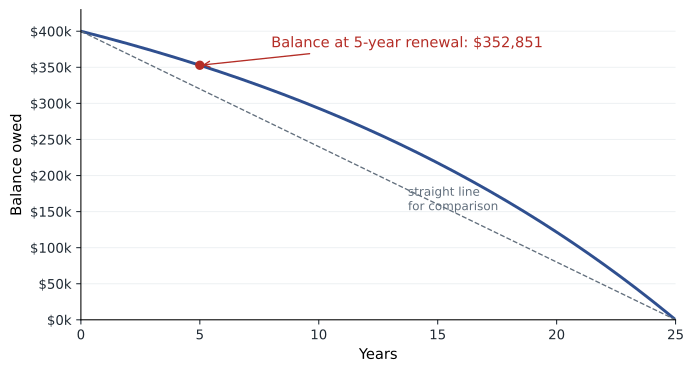
For the same mortgage, what is the balance at the end of a 5-year term, and how much interest was paid during the term?
Show solution
- k = 60. Balance = $400,000 × 1.0039524^60 − $2,278.83 × (1.0039524^60 − 1) ÷ 0.0039524 = $352,850.81.
- Principal repaid = $400,000 − $352,850.81 = $47,149.19.
- Interest paid = 60 × $2,278.83 − $47,149.19 = $136,729.80 − $47,149.19 = $89,580.61.
Answer: At renewal the couple still owes $352,850.81. Of the $136,730 paid over the term, about two-thirds was interest. The new payment will depend on the renewal rate.
Paying a loan off faster
Because interest is charged on the outstanding balance, anything that reduces the balance sooner saves interest: a shorter amortization, extra payments, lump-sum prepayments or more frequent payments. The savings are largest early in the loan, when the balance is highest.
Worked problem
Accelerated biweekly payments
Instead of $2,278.83 a month, the couple pays half that amount, $1,139.42, every two weeks (accelerated biweekly). How long does it take to repay the mortgage, and how much interest is saved?
Show solution
- 26 payments a year: equivalent biweekly rate = 1.02395^(2/26) − 1 = 0.0018226.
- n = −ln(1 − $400,000 × 0.0018226 ÷ $1,139.42) ÷ ln(1.0018226) ≈ 560.7 payments, or about 21.6 years.
- Interest ≈ 560.7 × $1,139.42 − $400,000 = $238,902.
- Interest with monthly payments = 300 × $2,278.83 − $400,000 = $283,649.
- Saving ≈ $283,649 − $238,902 = $44,747.
Answer: Accelerated biweekly payments repay the mortgage about 3.4 years sooner and save about $44,700 in interest. The trick is that 26 half-payments equal 13 monthly payments a year, one extra payment annually.
Worked problem
25 years or 30 years?
First-time buyers can choose a 30-year amortization on an insured mortgage. Compare the payment and total interest on the $400,000 mortgage at 4.79 % compounded semi-annually over 25 and 30 years, assuming the rate stays the same.
Show solution
- 25 years: PMT = $2,278.83; total interest = $283,649.
- 30 years: n = 360; PMT = $400,000 × 0.0039524 ÷ (1 − 1.0039524^−360) = $2,084.87.
- Total interest over 30 years = 360 × $2,084.87 − $400,000 = $350,553.
Answer: The 30-year amortization lowers the payment by about $194 a month but adds about $66,900 of interest.
Breaking or refinancing a mortgage
A closed Canadian mortgage cannot be paid off early, beyond its prepayment privileges, without a penalty. For a variable-rate mortgage the penalty is usually three months' interest. For a fixed-rate mortgage it is usually the greater of three months' interest and the interest rate differential (IRD), which compensates the lender for the lower rate it will earn by relending the money for the rest of the term. Lenders calculate the IRD in different ways, and on a large balance with several years left it can run to many thousands of dollars, so borrowers should ask for a written penalty quote before breaking a term to refinance or sell.
Worked problem
Three months' interest
Shortly before renewal, the couple from the earlier example must sell and break the mortgage, owing about $352,850.81 at 4.79 %. If the penalty is three months' interest, roughly how much is it?
Show solution
- Three months' interest ≈ $352,850.81 × 0.0479 × 3 ÷ 12 = $4,225.39.
- Had they been able to wait until the term ended, no penalty would apply, because the contract would have ended.
Answer: Breaking the mortgage mid-term would cost about $4,225, more if the IRD were larger; waiting until the term ends avoids the penalty.
# Amortization schedule and balance after k payments
def payment(pv, i, n): return pv * i / (1 - (1 + i) ** -n)
def schedule(pv, i, n):
    pmt = round(payment(pv, i, n), 2)
    bal, rows = pv, []
    for k in range(1, n + 1):
        interest = round(bal * i, 2)
        principal = bal if k == n else round(pmt - interest, 2)
        bal = round(bal - principal, 2)
        rows.append((k, round(interest + principal, 2), interest, principal, bal))
    return rows
for row in schedule(6000, 0.0075, 6):
    print(row)
p = 1.02395 ** (1 / 6) - 1          # 4.79% compounded semi-annually, monthly payments
pmt = round(payment(400000, p, 300), 2)
bal60 = 400000 * (1 + p) ** 60 - pmt * ((1 + p) ** 60 - 1) / p
print("Canadian mortgage payment", pmt, "balance after 60:", round(bal60, 2))
i = 0.0625 / 12                      # 6.25% compounded monthly
pmt = round(payment(400000, i, 360), 2)
bal60 = 400000 * (1 + i) ** 60 - pmt * ((1 + i) ** 60 - 1) / i
print("US mortgage payment", pmt, "balance after 60:", round(bal60, 2))(1, 1026.41, 45.0, 981.41, 5018.59) (2, 1026.41, 37.64, 988.77, 4029.82) (3, 1026.41, 30.22, 996.19, 3033.63) (4, 1026.41, 22.75, 1003.66, 2029.97) (5, 1026.41, 15.22, 1011.19, 1018.78) (6, 1026.42, 7.64, 1018.78, 0.0) Canadian mortgage payment 2278.83 balance after 60: 352850.81 US mortgage payment 2462.87 balance after 60: 373348.88
Common mistakes
MistakeUsing the nominal rate divided by 12 for a mortgage compounded semi-annually.
InsteadConvert to the equivalent monthly rate, (1 + j/2)^(1/6) − 1.
MistakeAssuming half the loan is repaid halfway through the amortization.
InsteadEarly payments are mostly interest; compute the balance with the formula.
MistakeConfusing the term with the amortization period.
InsteadThe term is the contract length; the amortization is the full repayment period.
MistakeLeaving the final payment unadjusted in a schedule.
InsteadAdjust the last payment so the balance ends at exactly zero.
MistakeIgnoring prepayment options.
InsteadExtra or more frequent payments early in the loan save the most interest.
Summary and key terms
- A loan is the present value of its payments.
- Each payment covers the interest on the balance first; the rest reduces principal.
- An amortization schedule tracks interest, principal and balance for every payment.
- The balance at any time is the future value of the loan minus the future value of the payments made.
- Canadian fixed mortgage rates compound semi-annually; payments are a general annuity.
- Mortgages are renewed at the end of each term until the amortization ends.
- Shorter amortizations and extra payments save large amounts of interest.
- Amortization
- Repaying a loan through regular payments of interest and principal.
- Amortization schedule
- A table of each payment's interest, principal and resulting balance.
- Amortization period
- The time needed to repay a loan in full at the scheduled payment.
- Term
- The length of the current loan contract, which may be shorter than the amortization period.
- Outstanding balance
- The principal still owed at a given time.
- Prospective method
- Finding a balance as the present value of the remaining payments.
- Retrospective method
- Finding a balance as the future value of the loan minus that of the payments made.
- Down payment
- The part of a purchase price paid from the buyer's own funds.
- Mortgage insurance
- Insurance that protects the lender when the down payment is small.
- Prepayment
- Paying more than the scheduled amount to reduce the balance faster.
Practice problems
Work each problem on paper first, then reveal the answer to check.
What monthly payment repays $18,000 over 4 years at 7.5 % compounded monthly?
Show answer
$435.22.
A loan of $50,000 at 6 % compounded monthly has a payment of $966.64 over 5 years. What is the first payment's interest?
Show answer
$250.00.
In the same loan, what is the principal in the first payment?
Show answer
$716.64.
What is the balance on that loan after 24 payments?
Show answer
About $31,774.
What is the equivalent monthly rate for 5.2 % compounded semi-annually?
Show answer
About 0.42868 %.
Why does an accelerated biweekly plan repay a mortgage sooner?
Show answer
It makes the equivalent of 13 monthly payments a year.
A $300,000 loan at 6 % compounded monthly over 25 years. What is the payment?
Show answer
$1,932.90.
What is the total interest on that loan over 25 years?
Show answer
About $279,870.
What is the minimum down payment on an $800,000 home?
Show answer
$55,000 (5 % of $500,000 plus 10 % of $300,000).
A loan's final payment in a schedule is slightly different from the others. Why?
Show answer
Rounding the payment to the cent leaves a small difference to clear.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.