
CON-350 · Lesson 1 of 12 · 27 min
Why construction is risky
Every construction project is a promise to deliver something that does not yet exist, on land that has never been fully explored, with people and materials that have not yet been hired or bought, at a price agreed before most of the uncertainty has gone away. That is a description of risk. Construction is not unusually careless; it is unusually exposed. Each project is a one-off prototype, built outdoors, by a temporary organization of dozens of firms, under contracts that try to fix price and time long before the facts are known. This course is about how the industry identifies those risks, decides who should carry each one, prices and funds them, and transfers some of them to insurers and sureties.
The course builds on several earlier ones. CON-220 covers the law of contracts, changes, delay, liens, prompt payment and disputes. CON-300 shows how risk enters a bid price, CON-310 how contingency is tracked in the cost report, CON-320 how a surety judges a contractor's finances, CON-330 how subcontractors are prequalified and managed, and CON-340 how risk shifts between delivery methods. Here we bring those threads together and go deeper on the risk process itself, on the clauses that allocate risk, and on insurance and bonding. Nothing in this course is legal or insurance advice; policies, bonds and contracts must always be read in full, with professional help.
What we mean by risk
In project management, a risk is an uncertain event or condition that, if it occurs, affects at least one project objective such as cost, time, quality, safety or reputation. Two features matter. First, a risk has a probability: it may or may not happen. Second, it has an impact: if it happens, it changes an outcome. A certainty is not a risk; it is a fact to be planned and priced. A problem that has already happened is not a risk either; it is an issue to be managed. Keeping these three categories apart is the first discipline of risk management, because each is handled differently.
| Term | Meaning | How it is handled |
|---|---|---|
| Known fact | Something certain, such as a winter shutdown or a fixed permit fee | Planned and priced directly in the estimate and schedule |
| Risk (threat) | An uncertain event with a negative effect, such as contaminated soil that may be found | Identified, analysed, responded to and funded through contingency or transfer |
| Risk (opportunity) | An uncertain event with a positive effect, such as a falling steel price | Identified and pursued; benefits may be shared under the contract |
| Issue | A risk that has occurred, or a problem that was never foreseen | Managed through the change, claim or problem-solving process |
| Uncertainty in estimates | The natural spread around a quantity or rate | Covered by estimating contingency (CON-300) and range estimates |
Opportunities deserve a mention because risk management is not only defensive. A design change that removes a temporary works package, a supplier that can deliver early, or a dry autumn that lets earthworks run ahead are all uncertain events with positive effects. Good registers record them alongside threats, and some contracts, especially target cost and integrated forms (CON-340), share the benefit when an opportunity is realised.
Why construction carries so much risk
Several structural features make construction riskier than most manufacturing or service work. A factory makes the same product thousands of times and can refine the process; a contractor builds a different building on a different site for a different owner every time. The work happens outdoors, exposed to weather and ground conditions. The project team is assembled for one job and dissolved at the end, so relationships and procedures are new. Price is usually fixed early, often on incomplete design. Payment flows down a long chain, so a failure at one link can affect everyone below it. Margins are thin, often a few per cent, so a modest loss can wipe out the profit of an entire job, and several bad jobs can sink a firm.
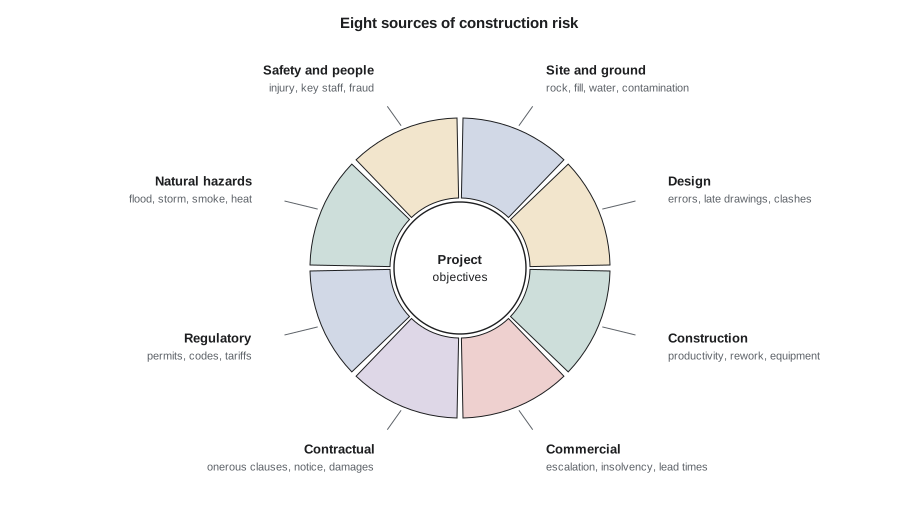
| Category | Typical risks |
|---|---|
| Site and ground | Unexpected rock, soft soils, groundwater, contamination, buried utilities, archaeology |
| Design | Errors and omissions, late or incomplete drawings, coordination clashes, constructability problems |
| Construction and productivity | Labour shortages, low productivity, rework, equipment breakdowns, poor subcontractor performance |
| Commercial and market | Material escalation, long lead times, subcontractor or supplier insolvency, interest rates, currency |
| Contractual and legal | Onerous clauses, unclear scope, disputes, liquidated damages, notice failures |
| Regulatory and political | Permits, inspections, code changes, tariffs, funding changes, community opposition |
| Environmental and natural hazards | Floods, storms, wildfire smoke, extreme heat or cold, earthquakes |
| Safety and people | Injuries and fatalities, key staff leaving, labour disputes, fraud |
Categories like these are useful as prompts when identifying risks, the subject of lesson 2. They are not watertight; contaminated soil is a site risk, an environmental risk, a regulatory risk and a cost risk all at once. What matters is that the team asks systematically about each area rather than relying on memory.
What the evidence says about overruns
Research on large projects has repeatedly found that cost and schedule overruns are common and that estimates are biased toward optimism. Studies of transport and infrastructure megaprojects by Bent Flyvbjerg and colleagues, covering thousands of projects in many countries, report that most exceed their budgets and that the distribution of overruns has a long tail: a minority of projects overrun by very large amounts. Building projects generally overrun less than tunnels, rail and information technology, but the pattern of optimistic estimates followed by growth is similar. The usual explanations are optimism bias, where planners underestimate difficulty in good faith, and strategic misrepresentation, where costs are understated to win approval.
Canadian and American examples show the range. Public reviews of troubled transit projects, hospital builds and stadiums in both countries have pointed to the same causes again and again: risk transferred to parties who could not manage it, design started before requirements were settled, ground conditions not investigated, unrealistic schedules, and weak contract administration. At the other end of the scale, small contractors fail every year because one job with an underpriced risk drains their working capital. CON-320 lesson 1 discusses contractor failure rates and their causes from the financial side.
The practical lesson is not that estimates are useless but that a single number is a poor description of an uncertain future. Lesson 3 shows how range estimates and Monte Carlo simulation turn an estimate into a distribution, and lesson 4 how contingency is sized from that distribution rather than as a flat percentage. Reference class forecasting, which adjusts an estimate using the actual outcomes of similar past projects, is another response to optimism bias that some public owners now require for major projects.
Worked problem
A loss on one job
A general contractor has annual revenue of $60 million, an average gross margin of 7 % and company overhead of $3.1 million. One $12 million job, bid at the average margin, suffers an unpriced rock excavation problem costing $1.2 million that cannot be recovered. What happens to company profit for the year?
Show solution
- Planned gross margin on all work: 0.07 × 60 = $4.2 million.
- Planned operating profit: 4.2 − 3.1 = $1.1 million.
- Loss on the rock: $1.2 million comes straight off gross margin.
- Revised operating profit: 1.1 − 1.2 = −$0.1 million.
Answer: One unpriced risk on one job turns a profitable year into a small loss. This is why contractors care so much about how risk is allocated and priced.
The risk management process
Most organizations follow a cycle based on international standards such as ISO 31000, Risk management: Guidelines, and on project management guidance such as the PMI standards (PMP-131 covers the PMI view). The cycle has five main steps, carried out continually rather than once.
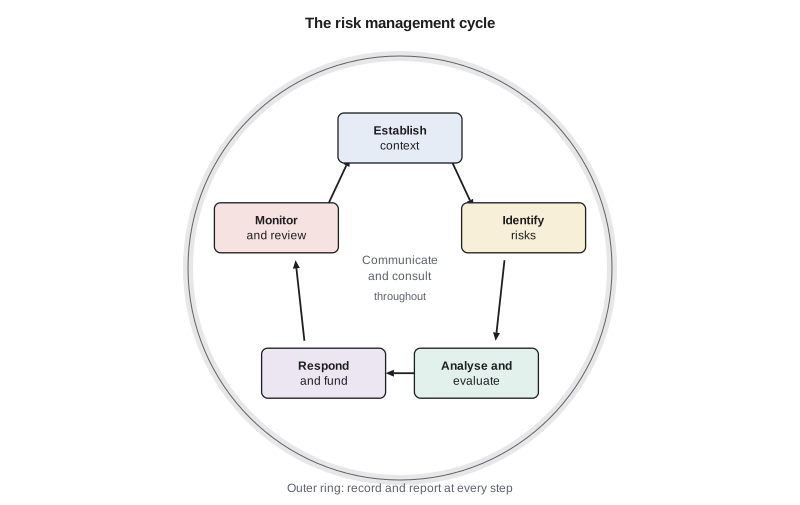
| Step | Key question | Main output | Lesson |
|---|---|---|---|
| Establish context | What are we trying to achieve, and how much risk can we accept? | Objectives, risk appetite, scoring scales | 1, 2 |
| Identify | What could happen? | Risk register with described risks and owners | 2 |
| Analyse and evaluate | How likely and how serious, and which matter most? | Scores, ranking, quantified ranges | 3 |
| Respond | What will we do about each one, and who pays? | Responses, contract allocation, insurance, bonds, contingency | 4 to 10 |
| Monitor and review | Is it working, and what has changed? | Updated register, contingency tracking, reports | 11, 12 |
The process applies at two levels. Owners manage project risk from the moment a business case is written; they decide which risks to keep and which to pass to designers and contractors through the contract. Contractors manage both the risks they accept under the contract and enterprise risks such as their backlog, bonding capacity and safety record. The same tools serve both, but the risk appetite differs: a public owner with a large portfolio can absorb variation that would ruin a small contractor.
Risk appetite and tolerance
Risk appetite is the amount and type of risk an organization is willing to pursue or keep to achieve its objectives. A contractor with a strong balance sheet might accept fixed-price work with ground risk; a smaller firm might decline it or insist on a differing site conditions clause. Tolerance turns appetite into thresholds, for example 'no single risk with an expected cost above 2 % of contract value may be left unmitigated' or 'the project must have at least an 80 % chance of finishing within budget'. Setting these thresholds early lets the team decide consistently which risks need action and which can simply be watched.
# How much of a year's profit can one risk consume? (illustrative)
revenue = 60_000_000
margin = 0.07
overhead = 3_100_000
profit = revenue * margin - overhead
print(f"Planned operating profit: {profit:,.0f}")
for loss in (250_000, 500_000, 1_000_000, 1_500_000):
    left = profit - loss
print(f"Unrecovered loss {loss:>9,}: profit {left:>10,.0f} ({loss / profit:.0%} of planned profit)")Planned operating profit: 1,100,000 Unrecovered loss 250,000: profit 850,000 (23% of planned profit) Unrecovered loss 500,000: profit 600,000 (45% of planned profit) Unrecovered loss 1,000,000: profit 100,000 (91% of planned profit) Unrecovered loss 1,500,000: profit -400,000 (136% of planned profit)
The table produced by the code is a simple way to show a board or owner why tolerance thresholds matter. For a contractor whose planned profit is around $1.1 million, a half-million-dollar unrecovered loss consumes almost half of a year's earnings. Owners face a parallel problem with their budgets and funding approvals, which are often fixed and politically difficult to increase.
Who should carry a risk?
A widely cited principle, often attributed to the work of Max Abrahamson on engineering contracts, is that a risk should be allocated to the party best able to control it, or, if no party can control it, to the party best able to bear it at the lowest cost. Applied honestly, the principle produces sensible contracts: the contractor carries the risk of its own productivity and methods, the owner carries the risk of the ground it chose to build on unless it has paid for a thorough investigation, and natural catastrophes are insured. Applied badly, owners push every risk onto contractors who then price it, decline to bid or fail. Lessons 5 and 6 explore allocation in detail, and CON-340 lesson 11 compares how delivery methods allocate the big risks.
| Response to a risk | What it means | Construction example |
|---|---|---|
| Avoid | Change the plan so the risk cannot occur | Relocate a building away from a known flood zone |
| Reduce (mitigate) | Lower the probability or the impact | Extra boreholes; early procurement of switchgear |
| Transfer | Move the financial consequence to another party | Insurance, surety bonds, subcontract terms, fixed-price contracts |
| Share | Split the consequence between parties | Escalation clause with a band; target cost pain/gain share |
| Accept (retain) | Keep the risk and fund it | Contingency, deductibles, self-insurance |
| Exploit or enhance | Increase the chance or benefit of an opportunity | Value engineering incentive; early completion bonus |
Transfer deserves a word of caution. Transferring a risk does not make it disappear. If a subcontractor that has accepted a risk cannot pay for it, the risk returns to the contractor; if the contractor cannot pay, it returns to the owner, sometimes with delay and litigation added. Insurance and surety exist precisely because they put a financially strong third party behind the transfer. That is why lessons 7 to 10 spend so much time on what policies and bonds actually cover.
Common mistakes
MistakeTreating a known cost, such as a scheduled winter shutdown, as a risk covered by contingency.
InsteadPrice known costs directly; reserve contingency for genuine uncertainty.
MistakeAssuming a risk has gone away once it is transferred in the contract.
InsteadCheck that the receiving party can actually manage and pay for it, and back the transfer with insurance or bonds where needed.
MistakeRelying on a single-point estimate for a complex project.
InsteadUse ranges and probabilistic methods to show the spread of possible outcomes.
MistakeIgnoring opportunities.
InsteadRecord and pursue opportunities in the same register as threats.
MistakeDoing risk management once at bid time and filing the register.
InsteadRun the cycle continually and review the register at regular project meetings.
Summary and key terms
- A risk is an uncertain event or condition that, if it occurs, affects a project objective; facts are priced and issues are managed.
- Construction is risky because each project is a one-off prototype, built outdoors by a temporary team, priced early, paid through a long chain and earning thin margins.
- Research on large projects shows frequent overruns with a long tail, caused by optimism bias and strategic misrepresentation as well as genuine uncertainty.
- The risk management cycle is establish context, identify, analyse and evaluate, respond, and monitor and review, with communication throughout.
- Risk appetite and tolerance thresholds let a team decide consistently which risks need action.
- Risks should go to the party best able to control them, or best able to bear them at least cost.
- Responses are avoid, reduce, transfer, share and accept for threats, and exploit or enhance for opportunities; transfer does not eliminate risk.
- Risk
- An uncertain event or condition that, if it occurs, affects at least one project objective.
- Issue
- A risk that has occurred or a problem that is now being managed.
- Opportunity
- A risk with a positive effect.
- Risk appetite
- The amount and type of risk an organization is willing to pursue or keep.
- Risk tolerance
- A threshold that turns risk appetite into a measurable limit.
- Optimism bias
- The tendency to underestimate the cost, time and difficulty of future work.
- Strategic misrepresentation
- Deliberately understating cost or risk to win approval or a contract.
- Reference class forecasting
- Adjusting an estimate using actual outcomes of a class of similar past projects.
- Risk transfer
- Moving the financial consequence of a risk to another party.
- Enterprise risk
- A risk to the organization as a whole rather than to one project.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Is a known increase in a permit fee a risk?
Show answer
No; it is a known fact and should be priced directly.
Give two features of construction that make it riskier than manufacturing.
Show answer
Any two of: one-off projects, outdoor work, temporary teams, early fixed prices, long payment chains, thin margins.
What are the two dimensions used to describe a risk?
Show answer
Probability and impact.
Name the five main steps of the risk management cycle.
Show answer
Establish context, identify, analyse and evaluate, respond, monitor and review.
A contractor's planned profit is $900,000 and an unrecovered loss of $360,000 occurs. What share of profit is lost?
Show answer
360,000 ÷ 900,000 = 40 %.
What is the difference between risk appetite and risk tolerance?
Show answer
Appetite is the general willingness to take risk; tolerance sets measurable thresholds.
State the usual principle for allocating a risk.
Show answer
To the party best able to control it, or if none can, the party best able to bear it at least cost.
Why does transferring a risk not eliminate it?
Show answer
If the receiving party cannot pay, the consequence flows back up the chain.
Give an example of sharing a risk.
Show answer
An escalation clause with a band, or a pain/gain share under a target cost contract.
What is reference class forecasting?
Show answer
Adjusting an estimate using the actual outcomes of similar past projects.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.