
BUS-101 · Lesson 4 of 12 · 28 min
Entrepreneurship and small business
Entrepreneurs start businesses by spotting an opportunity, gathering resources and taking a risk that the opportunity is real. Small businesses are the result of that process, and they are the backbone of employment in both Canada and the United States. This lesson looks at who entrepreneurs are, why small businesses matter, how to test an idea, how to calculate the break-even point, what a business plan contains, where start-up money comes from and why so many new businesses fail.
What entrepreneurs do
An entrepreneur organizes resources to pursue an opportunity in the face of uncertainty. Some entrepreneurs build high-growth start-ups backed by investors; far more open restaurants, trades businesses, shops, consulting practices and online stores that aim to provide a good living rather than to grow huge. Researchers often distinguish opportunity entrepreneurs, who start a business to pursue an idea, from necessity entrepreneurs, who start one because they lack other work. Both matter.
Successful entrepreneurs tend to share a few habits more than any personality type: they talk to customers early, test ideas cheaply before committing large sums, watch cash closely, learn from failure and ask for help. Being your own boss also brings long hours, irregular income and personal financial risk, which are worth weighing honestly before starting.
Why small business matters
Small businesses dominate the business landscape. According to the US Small Business Administration's Office of Advocacy, in figures released in February 2026 there were about 36.2 million small businesses in the United States, 99.9 % of all businesses, and they employed about 62.3 million people, 45.9 % of private-sector workers. The great majority have no employees at all: they are sole proprietors and freelancers. Small businesses have also created a large share of net new jobs over recent decades.
Small firms bring competition and new ideas to markets, serve local needs that large firms overlook, and give people a path to independence and wealth. They also face real disadvantages: less bargaining power with suppliers, higher borrowing costs, thin management teams and greater vulnerability to a single bad year or the loss of one big customer.
Testing an idea
Most failed businesses did not fail because the founders worked too little. They failed because too few customers wanted what they offered at a price that covered costs. Testing an idea before investing heavily is therefore one of the most valuable things a founder can do. Useful steps include talking to twenty or thirty potential customers about their problem (not your solution), studying competitors and their prices, estimating the size of the market, building a simple version or a pre-order page, and measuring whether people will actually pay. This approach is sometimes called the lean start-up method: build a minimum viable product, measure what customers do, learn and adjust.
Worked problem
Sizing a market
A founder plans a mobile bicycle repair service in a city with 650,000 adults. Surveys suggest 30 % of adults own a bicycle, 40 % of owners get it serviced each year and the average spend is $90. The founder thinks a 5 % share of this spending is achievable in year two. Estimate the market and the founder's target revenue.
Show solution
- Bicycle owners = 650,000 × 30 % = 195,000.
- Owners who pay for service each year = 195,000 × 40 % = 78,000.
- Total annual market = 78,000 × $90 = $7,020,000.
- Target revenue at a 5 % share = 5 % × $7,020,000 = $351,000.
- The founder should check these assumptions with local data and competitor counts, since each one multiplies through.
Answer: The serviceable market is about $7 million a year, and a 5 % share would be about $351,000 of revenue. Because the estimate multiplies several assumptions, a 20 % error in each can change the answer by much more.
Break-even analysis
Before opening, every founder should know the break-even point: the level of sales at which revenue exactly covers costs, so profit is zero. To find it, split costs into fixed costs, which do not change with the number of units sold in the short run (rent, insurance, salaries, loan payments), and variable costs, which rise with each unit (materials, packaging, sales commissions, payment fees). Each unit sold contributes its price minus its variable cost toward covering fixed costs.
Worked problem
Break-even for a candle maker
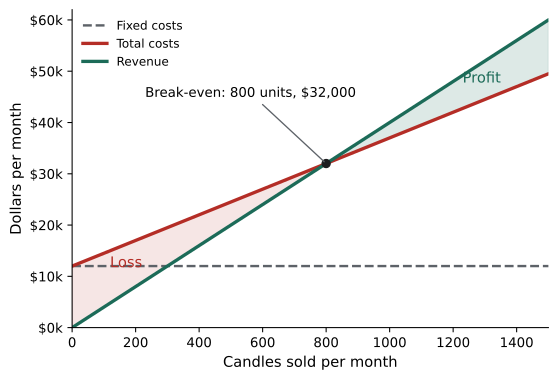
A candle maker sells candles for $40 each. Wax, wicks, fragrance, jars, packaging and payment fees cost $25 per candle. Monthly fixed costs, including studio rent, insurance, software and a part-time assistant, are $12,000. How many candles must she sell each month to break even, and what profit does she make at 1,100 candles?
Show solution
- Contribution per candle = $40 − $25 = $15.
- Break-even units = $12,000 ÷ $15 = 800 candles a month.
- Break-even revenue = 800 × $40 = $32,000.
- At 1,100 candles, contribution = 1,100 × $15 = $16,500.
- Profit = $16,500 − $12,000 = $4,500 a month.
Answer: She breaks even at 800 candles ($32,000 of sales) a month and earns $4,500 a month at 1,100 candles. Raising price, cutting variable cost or cutting fixed cost would all lower the break-even point.
Break-even analysis also shows how risky a plan is. The margin of safety is how far expected sales are above break-even: if expected sales are 1,100 units and break-even is 800, sales can fall by 300 units, or 27 %, before the business loses money. A business with high fixed costs and a small margin of safety is fragile.
The business plan
A business plan is a written description of the business and how it will succeed. Its main value is to force the founder to think things through; it is also what banks, investors and some government programs ask to see. A typical plan includes:
- An executive summary of the whole plan in a page or two.
- A description of the business, its products or services and its legal form.
- Market analysis: customers, market size, trends and competitors.
- A marketing and sales plan: positioning, pricing, channels and promotion.
- An operations plan: location, suppliers, equipment, staffing and key processes.
- The management team and advisers.
- Financial projections: start-up costs, a sales forecast, a projected income statement, cash flow forecast and balance sheet for at least three years, plus break-even analysis.
- The funding request: how much money is needed, what it is for and how it will be repaid or rewarded.
Start-up costs and cash
Founders routinely underestimate how much money they need. Start-up costs include equipment, renovations, opening inventory, deposits, legal and registration fees, a website and initial marketing. On top of these, a new business needs working capital to pay bills while sales build up, because customers often pay later than suppliers and staff need to be paid. Running out of cash, even while profitable on paper, is one of the most common reasons new businesses fail.
Worked problem
Start-up budget and runway
A founder opening a small physiotherapy clinic estimates start-up costs of $85,000 for equipment, leasehold improvements, deposits and fees. Monthly fixed costs will be $22,000. In the first six months, the clinic expects to cover 40 %, 55 %, 70 %, 80 %, 90 % and 100 % of its fixed costs from contribution. How much total funding does the founder need before the clinic is self-supporting, and what buffer would be prudent?
Show solution
- Shortfall each month = $22,000 × (1 − coverage).
- Month 1: $13,200; month 2: $9,900; month 3: $6,600; month 4: $4,400; month 5: $2,200; month 6: $0.
- Total operating shortfall = $13,200 + $9,900 + $6,600 + $4,400 + $2,200 = $36,300.
- Total funding = $85,000 + $36,300 = $121,300.
- A buffer of, say, three months of fixed costs ($66,000) or at least 25 % of the total protects against slower growth; total ≈ $150,000 to $187,000.
Answer: The founder needs about $121,000 at minimum and should seek roughly $150,000 or more, because sales almost always build more slowly than planned.
Sources of financing
Small businesses are financed mainly by debt (money borrowed and repaid with interest) and equity (money invested in exchange for ownership). Most start with the founder's own savings, sometimes called bootstrapping, plus money from family and friends. Banks lend to established businesses with cash flow and security, and usually want a personal guarantee from the owner of a new business. Equity investors, such as angel investors and venture capital funds, invest in a small number of high-growth companies in exchange for shares and influence. Other sources include equipment leasing, supplier credit, crowdfunding and government programs.
US programs include the Small Business Administration's 7(a) loan guarantee program, the largest, under which the SBA guarantees part of loans made by participating lenders up to $5 million; the 504 program for real estate and major equipment; SBA microloans of up to $50,000 through nonprofit intermediaries; Small Business Investment Companies; and state and local programs. Program limits change, so check the current terms.
| Source | Debt or equity | Advantages | Drawbacks |
|---|---|---|---|
| Personal savings | Equity | Keeps full control; no repayment | Personal risk; limited amount |
| Family and friends | Either | Flexible and fast | Can strain relationships; put terms in writing |
| Bank loan or line of credit | Debt | Keeps ownership; interest is deductible | Needs cash flow, security and often a personal guarantee |
| Government-backed loan | Debt | Easier approval for new businesses | Fees, paperwork and limits |
| Angel investors and venture capital | Equity | Large sums, advice and contacts | Give up ownership and some control; suited only to high-growth firms |
| Crowdfunding | Either, or pre-sales | Tests demand while raising money | Public failure risk; platform fees; securities rules for equity |
Why businesses fail and how they survive
Many new businesses do not survive. Bureau of Labor Statistics data on establishment survival have long shown that roughly one in five new private businesses closes within its first year and roughly half within five years, with variation by industry and economic conditions. Common reasons include too little demand, poor cash management, too little starting capital, weak management and competition.
Founders can improve their odds by testing demand before spending heavily, keeping fixed costs low, forecasting cash monthly, building a cash buffer, getting good advice from accountants, mentors and small business centers, and being willing to adjust the plan as they learn. Failure is also not the end: many successful entrepreneurs started more than one business before one worked.
Whatever the source, founders should match the type of money to its use. Long-lived assets such as equipment are best financed with term loans or leases repaid over the asset's life; seasonal swings in inventory and receivables suit a line of credit; and risky, unproven ideas suit the founder's own money or equity investors who expect some ventures to fail. Using a short-term line of credit to buy equipment, for example, can leave a business scrambling when the bank reviews the line.
Common mistakes
MistakeAssuming that if you build it, customers will come.
InsteadTest demand with real customers and real prices before investing heavily.
MistakeConfusing profit with cash.
InsteadForecast cash month by month; a profitable business can still run out of money.
MistakeUnderestimating start-up costs and the time to reach break-even.
InsteadAdd a buffer of several months of fixed costs to your funding request.
MistakeLocking in high fixed costs too early.
InsteadKeep fixed costs low until sales are proven; lease or share space and equipment.
MistakeWriting a business plan and never using it.
InsteadUse the plan's forecasts as a yardstick and update them monthly.
Summary and key terms
- Entrepreneurs organize resources to pursue opportunities under uncertainty.
- Small businesses are 99.9 % of US businesses and employ about 46 % of private-sector workers.
- Testing ideas with customers before investing heavily reduces the risk of failure.
- Break-even units equal fixed costs divided by contribution per unit.
- A business plan covers the market, marketing, operations, management, finances and funding.
- Start-up funding must cover both start-up costs and losses until break-even, plus a buffer.
- Financing comes from savings, family, banks, SBA-backed loans, investors and crowdfunding.
- Entrepreneur
- A person who organizes resources to pursue an opportunity under uncertainty.
- Small business
- In SBA statistics, generally a business with fewer than 500 employees.
- Minimum viable product
- The simplest version of a product that lets you learn from real customers.
- Fixed cost
- A cost that does not change with sales volume in the short run.
- Variable cost
- A cost that rises with each unit produced or sold.
- Contribution margin
- Price minus variable cost per unit.
- Break-even point
- The sales level at which profit is zero.
- Margin of safety
- How far expected sales exceed break-even sales.
- Working capital
- Money needed to run the business day to day.
- Equity financing
- Money raised by selling ownership.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Price $25, variable cost $15, fixed costs $9,000 a month. Break-even units?
Show answer
900 units.
In that case, what is break-even revenue?
Show answer
$22,500.
Expected sales 1,200 units, break-even 900. Margin of safety as a percentage of expected sales?
Show answer
25 %.
Name four sections of a business plan.
Show answer
Any four of summary, description, market, marketing, operations, management, financials, funding request.
What is bootstrapping?
Show answer
Funding a business from the founder's own resources and early revenue.
Name one advantage and one drawback of equity financing.
Show answer
Advantage: no repayment; drawback: giving up ownership and control.
Why do profitable businesses sometimes run out of cash?
Show answer
Customers pay later than costs are due, and growth ties up cash in inventory and receivables.
A market has 40,000 buyers spending $200 a year. What is a 3 % share worth?
Show answer
$240,000 a year.
What does the SBA 7(a) program do?
Show answer
Guarantees part of loans made by lenders to small businesses, up to $5 million.
Give two ways to lower a break-even point.
Show answer
Raise price, cut variable cost per unit or cut fixed costs.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.