
SLS-256 · Lesson 7 of 12 · 20 min
Extended warranties and service plans
▶ Video coming soon A video version of this lesson is on the way.
When Walter Sikorski chose his refrigerator in lesson 4, Aiden still had one more option to explain: a five-year protection plan for 189 dollars. Walter folded his arms. "My son says these are a rip-off," he said. "The store makes all its money on them." Aiden had heard the same thing from his own father. He had also spent that Wednesday's clinic with Carl going through the plan's terms line by line, and he knew the honest answer was neither "it's a rip-off" nor "you need this". It depended on what Walter already had and what he wanted.
Extended warranties, also called protection plans or service contracts, are among the most debated products in retail. They can give real peace of mind and save customers money on expensive repairs. They are also highly profitable for stores, often sold under pressure, and sometimes overlap with protection the customer already has. This lesson explains what they are, how they relate to the warranties the customer gets anyway, the rules that apply, and how to present them honestly.
Four layers of protection
A customer buying a big item may already be protected in several ways before any plan is offered. Sellers need to understand each layer, because customers often confuse them and because overlap is the main reason a plan may not be worth buying.
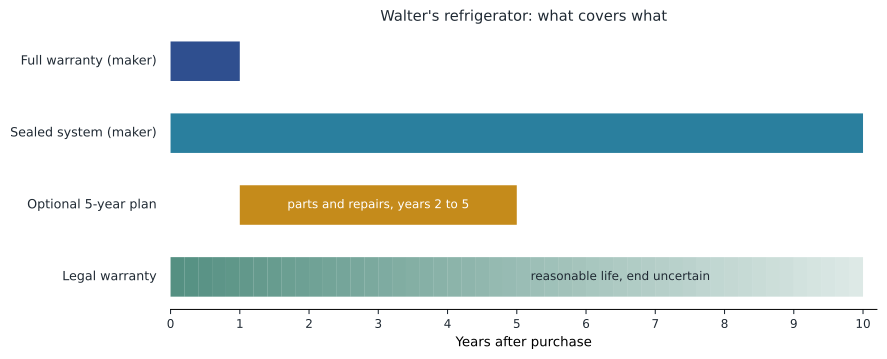
- The law. Saskatchewan's Consumer Protection and Business Practices Act gives every consumer statutory warranties that a product is of acceptable quality, fit for its purpose and durable for a reasonable time. A retailer cannot exclude them. A refrigerator that fails after two years may still be covered if two years is not a reasonable life for it.
- The manufacturer's warranty. Most appliances, electronics and mattresses come with a written warranty from the manufacturer, such as one year on parts and labour, with longer coverage on specific parts like a refrigerator's sealed system or a mattress's support core.
- The store's own policies. Juniper & Pine's 30-day return policy on most stock items, its 90-night mattress comfort exchange and its delivery-damage guarantee are store promises, separate from warranties.
- An optional plan. A protection plan is a separate contract, sold for a price, that adds coverage beyond the manufacturer's warranty, extends it in time, or covers things the warranty does not, such as accidental stains on upholstery.
What a protection plan covers
Plans differ widely, so the seller must know the actual terms of the plans their store sells. Juniper & Pine's plans are administered by an outside company, the plan administrator, which handles claims and pays for repairs. The store sells the plan and receives part of the price. Carl's checklist of what to know about any plan was short.
- What is covered. Mechanical and electrical failure, power surges, accidental stains, rips or burns on upholstery, or a combination.
- What is excluded. Cosmetic damage, misuse, commercial use, pet damage on many furniture plans, and failures already covered by the manufacturer.
- When it starts and ends. Many appliance plans start the day of purchase but pay only after the manufacturer's warranty ends. Juniper & Pine's five-year appliance plan runs five years from delivery.
- How claims work. Whether service is in the home, whether there is a deductible, how long repairs take, and what happens if an item cannot be repaired, for example replacement or a store credit.
- Cancellation and transfer. Whether the customer can cancel for a refund, full within a short period and pro-rated after it, and whether the plan transfers if they sell the item.
| Plan | Price | Coverage | Main exclusions |
|---|---|---|---|
| Appliance, 5 years | 149 to 249 dollars by price band | Parts and labour for mechanical and electrical failure after the manufacturer's warranty, in-home service, food spoilage up to 250 dollars | Cosmetic damage, misuse, commercial use |
| Upholstery, 5 years | 199 to 349 dollars by price band | Accidental stains, rips, burns and broken mechanisms; cleaning and repair or replacement of the damaged part | Pet damage, wear and fading, damage from moving |
| Mattress protector (product, not plan) | 129 dollars | A waterproof cover that keeps the manufacturer's warranty valid by preventing stains | Not a service contract |
Is a plan worth it?
A plan is a form of insurance against repair costs. Like any insurance, the price is set so that, on average, the plan administrator and the store pay out less than customers pay in. That does not make every plan a bad buy, any more than home insurance is a bad buy. It means a customer is paying for certainty, and whether that is worth it depends on the item, the coverage already in place and how the customer feels about unexpected bills.
Worked problem
The cost of coverage per year
Walter's refrigerator costs 1,899 dollars. The manufacturer covers parts and labour for the first year and the sealed system for ten years. The five-year plan costs 189 dollars and covers parts and labour from delivery, so it adds parts and labour coverage in years 2 to 5. What does the plan cost per year of added coverage?
Show solution
- Years of added parts-and-labour coverage: years 2, 3, 4 and 5, so 4 years.
- Cost per added year:
- \[\frac{189}{4} = 47.25 \text{ dollars a year}\]
Answer: The plan costs about 47 dollars for each year of added coverage. The sealed system, the most expensive part to repair, is already covered for ten years by the manufacturer, which reduces what the plan adds.
Worked problem
Expected repair cost against the plan price
Suppose that, for this kind of refrigerator, about 1 in 5 units needs a repair outside the sealed system in years 2 to 5, and the average repair costs about 320 dollars. What is the expected repair cost for one refrigerator in that period, and how does it compare with the plan price?
Show solution
- Expected repair cost:
- \[\frac{1}{5} \times 320 = 64 \text{ dollars}\]
- Compare with the plan price of 189 dollars:
- \[189 - 64 = 125 \text{ dollars}\]
Answer: On these illustrative figures, an average buyer would spend about 64 dollars on repairs without the plan, 125 dollars less than the plan costs. The plan is worth more to a buyer who would find a 300-dollar surprise bill hard to manage, or who values in-home service and no paperwork, than to one who can absorb it. These repair figures are assumptions for the example; the seller should never invent failure rates for a customer.
Carl's view was that the seller's job is not to decide for the customer but to give them the facts they need: what they already have, what the plan adds, what it costs per year, and the main exclusions. Some customers buy for peace of mind, and that is a legitimate reason. Others decide to keep the money, and that is legitimate too.
When a plan makes more sense, and when less, can be summarized from experience rather than rules.
| A plan is more likely to suit a customer who | A plan is less likely to suit a customer who |
|---|---|
| Is buying an item that is expensive to repair, such as a front-load washer or a sectional with power recliners | Is buying an inexpensive item that would be replaced rather than repaired |
| Has pets, young children or heavy use that make accidents likely, and the plan covers them | Already has overlapping coverage, such as a long manufacturer warranty or a credit card that extends warranties |
| Would find an unexpected repair bill hard to manage | Prefers to set aside money for repairs and can absorb a surprise bill |
| Values in-home service and a single phone number | Is likely to replace the item soon for other reasons |
What the law says about plans
In Saskatchewan, a plan sold with a product is an additional written warranty on top of the statutory warranties, and it cannot take them away. If the plan's provider does not honour a valid claim within a reasonable time, the consumer may have the item repaired elsewhere and recover reasonable costs. Because the statutory warranties already require acceptable durability, sellers must never suggest that a customer without a plan has no protection after the manufacturer's warranty ends. Some extended warranties, especially on vehicles, can also fall under insurance rules, which is one reason stores sell plans through licensed administrators. Misrepresenting what a plan covers is an unfair practice under the Act and can be a misleading representation under the Competition Act.
Presenting the plan
Juniper & Pine trains its sellers to present plans in a set order, at the end of the product decision and before the order is written, so that the customer can decide calmly.
- Say what the customer already has: the manufacturer's warranty, the key part with long coverage, and the store's own policies.
- Say what the plan adds, in time and in coverage, and the main exclusion.
- Give the price and, where helpful, the cost per year of added coverage.
- Ask whether they would like it, accept the answer, and move on.
For Walter, Aiden's version took about a minute: "You already have a year of full coverage and ten years on the sealed system, which is the expensive part. The plan adds four more years of parts and labour, with in-home service, for 189 dollars, so about 47 dollars a year. It doesn't cover dents or scratches. Some people like knowing there won't be a repair bill; some would rather keep the money. Would you like it?" Walter thought about it and said no. "I fix things myself, mostly," he said. "But thank you for not making me feel stupid." Two weeks later he sent his daughter in to buy a washer and dryer, and asked for Aiden by name.
Making a claim
A protection plan is only as good as the experience of using it. Customers judge the store, not the plan administrator, when a claim goes badly, so Carl made sure Aiden could explain the claims process at the time of sale.
- Who to call. Most plans are run by an administrator with its own phone line and website. The plan document and the receipt both show the number.
- What to have ready. The plan or receipt number, the model and serial number, and a description of the problem. Photos help for fabric and finish claims.
- What happens next. The administrator approves the claim, then arranges a technician, a cleaning kit, a part or, if repair is not practical, a replacement or buyout as the terms allow.
- What is excluded. Damage from misuse, pets (unless covered), commercial use and normal wear are common exclusions. The seller should name the main ones at the sale.
| Claim | Likely outcome under a typical upholstery plan |
|---|---|
| Red wine spilled on a fabric cushion last night | Covered: accidental stain, reported promptly; cleaning kit or technician |
| Fabric worn thin on the arm after three years of daily use | Not covered: normal wear |
| A recliner mechanism that stops working in year 3 | Covered: mechanical failure after the maker's warranty |
| Scratches from a pet's claws | Usually excluded unless the plan includes pet damage |
Aiden added a line to his plan presentation: "If you ever need it, the number's on your receipt, and you can call me too if anything goes sideways." It took five seconds and made the plan feel like part of the store's service rather than a separate product sold by someone else. When a claim is refused, a seller who explained the exclusions honestly at the sale rarely loses the customer's trust; one who glossed over them usually does.
Common mistakes
MistakeTelling customers they have no protection once the manufacturer's warranty ends.
InsteadExplain the legal warranties that apply regardless of any plan.
MistakeSelling a plan without knowing its exclusions.
InsteadRead the terms of every plan you sell, including what is excluded and how claims work.
MistakePresenting a plan as necessary.
InsteadPresent it as an option, with what it adds and what it costs per year.
MistakeInventing failure rates to justify a plan.
InsteadUse only figures you can support, or describe risk in general terms.
MistakeIgnoring overlapping coverage the customer already has.
InsteadAsk about and mention long manufacturer warranties and card benefits.
Summary and key terms
- Customers have four layers of protection: the law, the manufacturer's warranty, the store's own policies and any optional plan.
- A protection plan is a separate contract that extends or adds coverage; its value depends on what it adds beyond what the customer already has.
- Sellers must know what each plan covers, excludes, when it runs, how claims work and how to cancel.
- Plans are priced so that average payouts are below the price, like insurance, so they suit some customers more than others.
- The law keeps legal warranties in place whether or not a plan is bought and prohibits misrepresenting plans.
- Presenting a plan means saying what the customer has, what the plan adds, its price and cost per year, then accepting the answer.
- Protection plan
- An optional contract, sold for a price, that adds repair or replacement coverage; also called an extended warranty or service contract.
- Plan administrator
- The company that handles claims and pays for repairs under a protection plan.
- Manufacturer's warranty
- The written warranty the maker provides with the product.
- Deductible
- An amount the customer pays toward each claim before the plan pays.
- Pro-rated refund
- A refund on cancellation that is reduced in proportion to the time the plan has run.
- Additional written warranty
- Saskatchewan's term for a warranty given beyond the statutory minimum, such as a protection plan.
Practice problems
Work each problem on paper first, then reveal the answer to check.
A 2,400-dollar washer has a one-year manufacturer warranty. A five-year plan from delivery costs 240 dollars. What is the cost per year of added coverage?
Show answer
It adds years 2 to 5, so 4 years; 240 ÷ 4 = 60 dollars a year.
If 1 in 4 units needs a 280-dollar repair during a plan's added years, what is the expected repair cost per unit?
Show answer
280 ÷ 4 = 70 dollars.
Give two reasons a plan may not suit a customer.
Show answer
Any two of: an inexpensive item, overlapping coverage, ability to absorb a repair bill, likely early replacement.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.