
CRE-330 · Lesson 1 of 12 · 29 min
Running a creator business: from hobby to enterprise
Most creators start by making things they enjoy and only later notice that they are running a business. Brand deals arrive, platform payments start, an editor needs paying, and suddenly there are contracts to sign, invoices to send and tax to plan for. CRE-302 showed how creators earn money and CRE-310 showed how brand partnerships are sold and delivered. This course is about what happens around and after the money arrives: choosing a business structure, reading and negotiating contracts, getting paid, keeping books, pricing for profit, handling income tax and sales tax, working with managers and agents, protecting intellectual property, insuring the business and saving for the future.
It is not legal, tax or accounting advice. Tax rates, thresholds and rules change every year and differ by state, so confirm current figures with the Internal Revenue Service (IRS), your state tax agency and a qualified professional before acting.
Why business skills matter for creators
Creative talent wins attention, but business skill decides whether a creator can keep going. Many creators with large audiences struggle financially because money comes in irregularly, a big share goes to fees and commissions, tax is not set aside, and contracts quietly give away valuable rights. Others with modest audiences build stable incomes because they price carefully, keep costs under control, own their content and plan ahead.
Think of a creator business as having four jobs that must all be done, whether by the creator, a team or outside professionals:
- Making: producing content and products people value.
- Selling: winning deals, setting prices and negotiating terms.
- Administering: contracts, invoices, bookkeeping, tax filings and insurance.
- Planning: budgets, cash reserves, investments in growth and the long-term future.
The first two are usually where creators spend their energy. This course concentrates on the last two, which are less glamorous but often make the biggest difference to what the creator actually keeps.
Hobby or business?
Tax authorities draw a line between a hobby and a business. The distinction matters because a business can deduct its expenses, and its losses may offset other income, while a hobby generally cannot.
In the US, Internal Revenue Code section 183 limits deductions for activities "not engaged in for profit." The IRS looks at factors such as whether you carry on the activity in a businesslike manner, the time and effort you put in, whether you depend on the income, your expertise, your history of income or losses and your expectation that assets will grow in value. An activity that makes a profit in at least three of five consecutive years is presumed to be a business. Hobby income must still be reported, but hobby expenses are not deductible: the suspension of miscellaneous itemized deductions that began in 2018 was made permanent by the One Big Beautiful Bill Act in 2025. Once you earn regular sponsorship income, you should expect to be treated as a business.
In practice, a creator who signs brand deals, sends invoices and earns platform revenue is running a business. The sensible response is to behave like one from the start: keep records, separate business and personal money, and make decisions with profit in mind.
The creator business model
A business model describes how an organization creates value, delivers it and captures some of it as revenue. For a creator, the main elements are:
- Audience: who watches, reads or listens, and why they stay.
- Value: what the content gives them, such as entertainment, education, inspiration or community.
- Revenue streams: platform payments, sponsorships, affiliates, memberships, products and services (covered in CRE-302).
- Costs: equipment, software, editing, travel, studio space, team, professional fees and platform or payment fees.
- Key partners: platforms, brands, agencies, managers, suppliers and collaborators.
- Key assets: the content library, the brand name, the audience relationship, email lists and skills.
The financial side of the model comes down to a simple identity: profit equals revenue minus costs. Everything in this course is about measuring each side accurately, increasing the gap between them and keeping as much of the result as the law allows.
From gross revenue to take-home pay
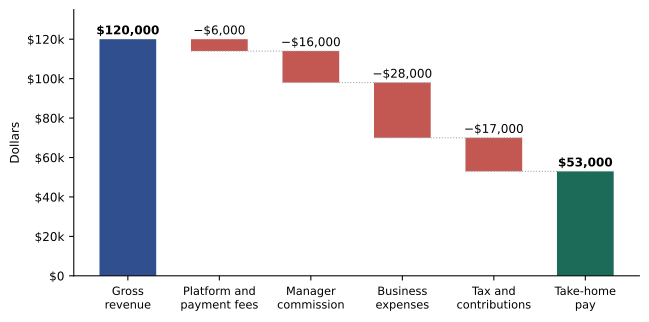
The headline figure in a brand deal or a platform dashboard is rarely what the creator keeps. Money passes through several layers before it reaches the creator's personal bank account:
- Platform and payment fees: platform revenue shares, marketplace commissions and card or payout fees.
- Representation fees: commissions to managers, agents or networks.
- Business expenses: editors, equipment, software, travel and other costs of running the business.
- Taxes: federal and state income tax and self-employment tax for Social Security and Medicare. Sales tax collected on merchandise is not income at all; it belongs to the state.
Worked problem
From gross to take-home
A creator's business earns $120,000 in a year: $80,000 from brand deals and $40,000 from platform and affiliate payments. Payment and platform fees take 5 % of all revenue. A manager takes 20 % of brand-deal income only. Business expenses are $28,000. Assume income tax and pension or self-employment contributions total about $17,000, an effective rate of roughly 24 % of profit. Estimate take-home pay.
Show solution
- Fees: 5 % × $120,000 = $6,000.
- Manager commission: 20 % × $80,000 = $16,000.
- Profit before tax: $120,000 − $6,000 − $16,000 − $28,000 = $70,000.
- Tax and contributions: about $17,000, or 17,000 ÷ 70,000 ≈ 24 % of profit. The effective rate is well below the top marginal rate because personal credits and lower brackets apply to the first dollars of income.
- Take-home: $70,000 − $17,000 = $53,000.
Answer: About $53,000, or 44 % of gross revenue. The exact tax depends on where the creator lives and the credits and deductions available, but the lesson is clear: plan from profit and take-home pay, not from headline revenue.
The first-year setup
A few practical steps in the first year make everything else easier. None of them is complicated, but each one is much harder to fix later.
| Step | What it involves in the US | Why it matters |
|---|---|---|
| Choose a structure | Sole proprietorship to start; consider an LLC or S corporation election later (lesson 2) | Affects tax, liability and paperwork |
| Register a business name | File an assumed name or "doing business as" (DBA) with your county or state if you use a name other than your own | Required by state law and by banks |
| Get an EIN | A free employer identification number from the IRS | Lets you avoid giving clients your Social Security number; needed for an LLC with employees or a corporation |
| Open a separate bank account | A business checking account and, ideally, a dedicated credit card | Clean records and easier tax returns |
| Set up bookkeeping | Accounting software or a structured spreadsheet | Records for Schedule C or business returns |
| Create templates | Invoice, contract checklist, rate card and Form W-9 | Consistency and faster deals |
| Review insurance | Equipment, liability and media liability (lesson 11) | Protects against expensive surprises |
Separating business and personal money deserves special emphasis. When every payment and expense runs through one personal account, bookkeeping becomes guesswork, deductible expenses are missed and, if the business is ever audited, the creator must reconstruct a year of transactions from memory. A separate account costs little and solves most of these problems at once.
Building a professional team
Few creators can be expert in law, tax, accounting and negotiation as well as in their craft. The usual professional team grows in stages:
- A bookkeeper or bookkeeping software to record transactions monthly.
- An accountant, ideally a Certified Public Accountant (CPA) or enrolled agent familiar with self-employed creators, to prepare tax returns, advise on structure and plan tax.
- A lawyer to review important contracts, register trademarks and handle disputes.
- A manager or agent to find deals and negotiate, when deal volume justifies the commission (lesson 11).
- A financial planner to help with retirement savings and investments once income is stable.
Professional help costs money, so compare the fee with what it saves or earns. Good advice pays for itself when it prevents an expensive mistake, recovers deductions or improves a deal.
Worked problem
Is an accountant worth it?
A creator has profit of $70,000 and has been preparing their own return. An accountant quotes $2,200 a year for bookkeeping review, the tax return and planning. The accountant expects to find $4,000 of missed deductible expenses and to save about $1,500 a year by better timing of retirement contributions. At a combined marginal tax rate of 33 %, is the fee worth paying?
Show solution
- Tax saved from missed deductions: 33 % × $4,000 = $1,320.
- Tax saved from better planning: $1,500.
- Total tax saved: $1,320 + $1,500 = $2,820.
- The accountant's fee is itself a deductible business expense, so its after-tax cost is $2,200 × (1 − 0.33) = $1,474.
- Net benefit: $2,820 − $1,474 = $1,346, plus hours of the creator's time and lower risk of errors.
Answer: Yes. The expected tax savings exceed the after-tax cost of the fee by about $1,350, before counting the value of time saved and reduced risk.
Records and how long to keep them
Good records support every number on a tax return. Keep invoices issued, receipts for expenses, bank and card statements, contracts, payment reports from platforms and brands, mileage logs and records of equipment purchases.
The IRS generally asks you to keep records for three years from the date you filed the return, six years if you underreported income by more than 25 %, seven years for claims involving bad debts or worthless securities, and indefinitely if you did not file or filed a fraudulent return. Keep employment tax records for at least four years. Many advisers simply recommend keeping everything for seven years.
A simple monthly routine works well: download statements, match each transaction to a receipt or invoice, categorize it, and store the documents in folders by year and month. Cloud storage with a backup is better than a shoebox.
Thinking about risk
A business plan should list the main risks and what will be done about them. For creators, common risks include losing access to a platform account, a brand dispute, an injury that stops production, equipment theft, a copyright or defamation claim, a large unexpected tax bill and the loss of a single big client. Each risk can be avoided, reduced, transferred (for example, to an insurer) or accepted. Later lessons cover the tools: contracts, cash reserves, tax planning, insurance and diversification.
Worked problem
A simple risk score
A creator rates risks by likelihood (1 to 5) and impact (1 to 5) and multiplies them. A tax bill they cannot pay is rated likelihood 3 and impact 5. Losing their main platform account is likelihood 2 and impact 5. Equipment theft is likelihood 2 and impact 3. Which risk should they tackle first?
Show solution
- Tax bill: 3 × 5 = 15.
- Platform account loss: 2 × 5 = 10.
- Equipment theft: 2 × 3 = 6.
Answer: The tax bill scores highest at 15, so setting aside tax money (lesson 9) comes first, followed by account security and diversifying channels, then equipment insurance.
How this course is organized
Lesson 2 compares business structures. Lessons 3 to 5 cover contracts: their anatomy, the rights clauses that matter most to creators, and how to review and negotiate them. Lessons 6 to 8 cover getting paid, bookkeeping and financial statements, and budgeting and pricing for profit. Lessons 9 and 10 cover income tax, pension or self-employment contributions, sales tax, gifted products and cross-border income. Lesson 11 covers managers, agents, insurance and intellectual property, and lesson 12 brings everything together in retirement planning and a capstone business plan.
Common mistakes
MistakeTreating the creator business as a hobby long after it earns regular income.
InsteadRun it as a business from the start: records, a separate account and profit-focused decisions.
MistakePlanning personal spending from gross revenue.
InsteadPlan from take-home pay after fees, commissions, expenses and tax.
MistakeMixing business and personal money in one account.
InsteadOpen a separate business account and card in the first year.
MistakeAvoiding professional help to save the fee.
InsteadCompare the after-tax cost of advice with the tax and risk it saves.
MistakeThrowing away receipts once the return is filed.
InsteadKeep records for the full period required by the tax authority.
Summary and key terms
- A creator business must make, sell, administer and plan; the last two often decide what the creator keeps.
- Tax authorities distinguish hobbies from businesses; regular sponsorship income usually means a business.
- Profit equals revenue minus costs, and take-home pay is what is left after fees, commissions, expenses and tax.
- Headline revenue can be more than double what the creator takes home.
- First-year setup includes a structure, name registration, a tax number, a separate account, bookkeeping, templates and insurance.
- Professional advice is worth paying for when its after-tax cost is less than the tax and risk it saves.
- Keep records for the full required period and manage key risks deliberately.
- Business model
- How a business creates, delivers and captures value.
- Profit
- Revenue minus costs.
- Take-home pay
- What the owner keeps after fees, expenses and tax.
- Section 183
- The hobby-loss rule limiting deductions for activities not engaged in for profit.
- EIN
- Employer identification number issued by the IRS.
- DBA
- A "doing business as" or assumed business name.
- CPA
- Certified Public Accountant.
- Marginal tax rate
- Tax on the next dollar of income.
- Record retention
- Keeping tax records for the required period, generally three to seven years.
- Risk score
- Likelihood multiplied by impact.
Practice problems
Work each problem on paper first, then reveal the answer to check.
Revenue $90,000, fees $4,500, commission $12,000, expenses $20,000. What is profit before tax?
Show answer
$53,500.
Name the four jobs of a creator business.
Show answer
Making, selling, administering and planning.
Why should business and personal money be separated?
Show answer
For clean records, captured deductions and easier audits.
A $1,800 accountant fee at a 30 % marginal rate has what after-tax cost?
Show answer
$1,260.
A risk with likelihood 4 and impact 2 scores what?
Show answer
8.
Give three signs that an activity is a business rather than a hobby.
Show answer
Separate records and account, a plan, regular revenue efforts, time invested, changes when results are poor.
What share of a $100,000 gross is take-home pay of $45,000?
Show answer
45 %.
Name four kinds of records a creator should keep.
Show answer
Invoices, receipts, statements, contracts, platform reports, mileage logs.
Name four ways to deal with a risk.
Show answer
Avoid, reduce, transfer or accept it.
Is sales tax or GST/HST collected part of the creator's income?
Show answer
No; it is held for the government.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.